BIEL: 400% Surge + AI Platform + VC Validation + Haleon + Veterinary Expansion = PPS / Revenue Explosion The macro wearable trend is the backdrop — but BIEL is positioned to cash in as ActiPatch becomes the therapeutic layer the entire sector is missing. The wearable-health boom — from Oura to Apple to WHOOP — is the wave, and BIEL is the only FDA-cleared PEMF engine ready to plug into it.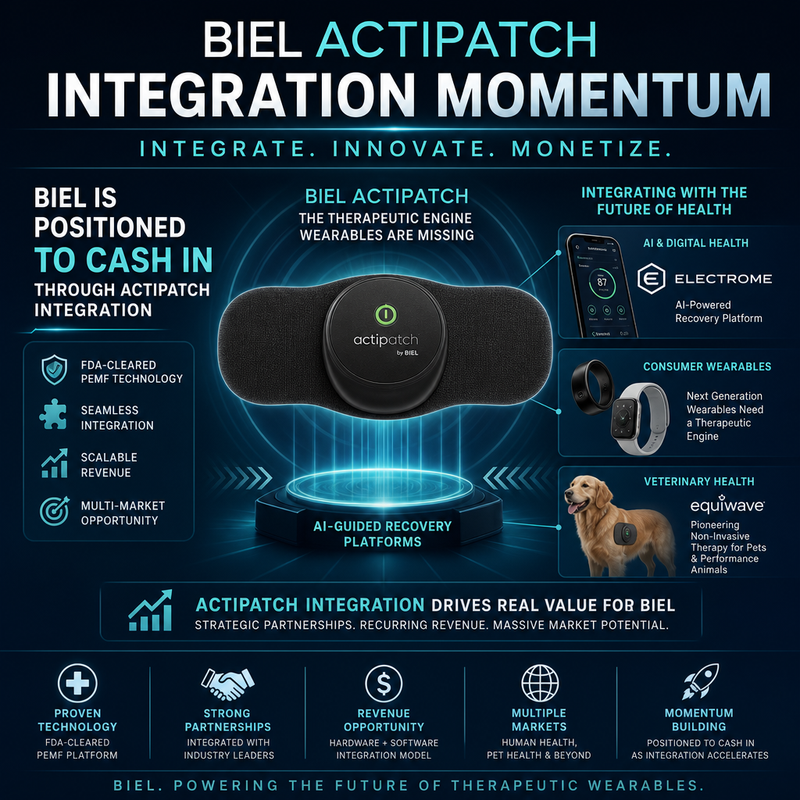
A PERFECT POWDER KEG
Supply squeeze. Multi-industry AI demand. OEM revenue explosion. Global consumer health. Institutional validation.
The setup is textbook.
A LITTLE SPARK LAUNCHES A SUPPLY SQUEEZE
Level 2 at Friday close shows the structural setup for a violent gap-up: Only 13M left @ .0004 and very thin above, versus nearly 300M @ .0002 just months ago.
The wall is gone. The fuse is lit.
BIEL’s Recent 400% Run Isn’t Just Big — It’s Historic
The move from .0001 to .0005 is a verified 400% gain, placing BIEL in the top 0.1% of all traded securities.
This triggers:
Algorithmic flags
Momentum scanners
Day-trader and quant-fund attention
Viral visibility on Webull, Robinhood, Stocktwits
This is how story stocks are born — and BIEL is still a microcap.
400% is the beginning, not the end.
Electrome: The AI Engine That Turns BIEL Into a Hot-Sector Hardware Play
Electrome is an AI-native therapeutics platform, and every node in that platform runs on BIEL-manufactured PEMF hardware.
This is the “Intel Inside” moment for bioelectric medicine.
AI is the hottest sector in the market.
Electrome is building an AI-guided care model.
BIEL is the exclusive OEM supplier powering it.
This is why the revenue math becomes explosive.
Capital Factory Validation = Institutional Credibility
Electrome is now backed by Capital Factory, one of the most respected early-stage VC groups in the U.S.
This matters because:
They vet venture-scale, high-growth startups
Their backing signals Electrome is real, scalable, investable
Electrome’s entire platform depends on BIEL hardware
BIEL is now indirectly VC-validated — a rarity for microcaps.
BIEL + Electrome AI Painkiller Is Huge
OEM Revenue Engine #1 — Human Health
Electrome’s rollout creates compounding hardware demand:
Phase 1 — PAINKILLER™ Launch
50k–150k units = $0.75M–$2.25M
Phase 2 — Multi-Vertical AI Expansion
Sleep, Recovery, Post-Surgical = $4M–$7M
Phase 3 — National Penetration
1% chronic pain market = $7.5M+ annually
2–3% penetration = $15M–$22M in high-margin OEM revenue
This is the kind of curve that re-rates a microcap overnight.
OEM Revenue Engine #2 — Veterinary AI ($120B Market)
A second massive growth engine:
Immediate cash flow
Lower regulatory barriers
Exploding demand for drug-free recovery
Electrome’s AI becomes the “brain” for animal recovery.
BIEL becomes the hardware backbone.
Veterinary Revenue Forecast
Phase 1: Elite performance animals = $500K–$1.2M
Phase 2: 5,000+ specialty clinics = $3M–$7.5M
Phase 3: Global pet wearables = $12M–$25M+ annually
OEM Revenue Engine #3 — Haleon: The Consumer Health Super-Vertical
Haleon (Advil, Voltaren, etc.) is the largest and fastest-moving vertical.
Why it matters:
Mass-market liquidity
Global distribution (100,000+ retail points)
Drug-free wellness demand
Electrome AI = the brain
BIEL hardware = the engine
Haleon Revenue Forecast
Phase 1: Premium pilots = $2M–$5M
Phase 2: Global rollout = $15M–$35M
Phase 3: Mass-market wearables + subscriptions ? $50M–$100M+ annually
The Unified “Intel Inside” Ecosystem
Across all three industries:
Electrome AI = the brain
BIEL PEMF hardware = the engine
Every user becomes a recurring hardware node
The ecosystem becomes closed-loop and proprietary
This is the holy grail of OEM business models.
Publicity Is the Catalyst — And PPS Momentum Delivers It for Free
A move to .003 makes BIEL the story stock of 2026 — a 3,000% gain from .0001.
That kind of move generates millions in free media coverage:
AI
Bioelectric medicine
Veterinary AI
Consumer health
A 400–3,000% microcap breakout
A national platform scaling
A hardware-inside narrative
This is how microcaps become national stories.
THE BIEL QUANTUM LEAP
BIEL is positioned to achieve in months what Amazon, Netflix, Apple, Google, Tesla, and Nvidia took decades to accomplish.
If BIEL delivers $2.5M in net profit, it could command a $2.5B market cap — equivalent to $0.10 PPS.
High-narrative disruptors (revenues doubling every year) routinely trade at P/E > 1,000.
Profitability Is Within Reach
BIEL has already shown it:
Q3 2021 profit: $22,381
Revenue: $414,700 (including $100K COVID relief)
With an ultra-lean model, sustained profitability is not theoretical — it’s imminent.
PPS Projections
.001 — Technical breakout (Ble Sky Breakout)
.003 — 3,000% gain as Electrome news spreads
.01 — cash flow positive/profitability confirmed (2026)
.10 — $2.5M profit (2027)
$1.00 — After debt payoff + buyback (2028)
Tax Advantage: A Hidden Accelerator
BIEL holds a $41M tax-loss carryforward, meaning the first $40M in profits are tax-free — accelerating net profitability.
Wearables Macro Trend + BIEL/Electrome Growth Engine
Oura was simply used as an example because their upcoming IPO is the most visible current signal of how much capital is flowing into the smart-ring / smart-watch space.
The broader message is that the entire sector is attracting massive investment, and that rising tide lifts every company operating anywhere near the wearable-health ecosystem.
While Oura was the easiest example to illustrate the trend, the same logic applies to all the major players building biometric platforms:
WHOOP
Apple Watch / Apple Health
Samsung Galaxy Ring
Fitbit (Google)
Garmin
Amazfit / Zepp Health
Ultrahuman Ring
Movano / Evie Ring
Circular Ring
All of these companies are racing toward the same endgame:
continuous sensing ? actionable insights ? personalized interventions.
That’s exactly why the sector’s growth matters — and why therapeutic technologies like BIEL’s PEMF hardware and Electrome’s AI-native platform fit naturally into where the industry is heading.
Summary
The wearable-health boom — from Oura to Apple to WHOOP — is the macro wave.
BIEL + Electrome is the microcap positioned directly in its path.
1