❤TOP 15 REASONS TO LOVE BIEL❤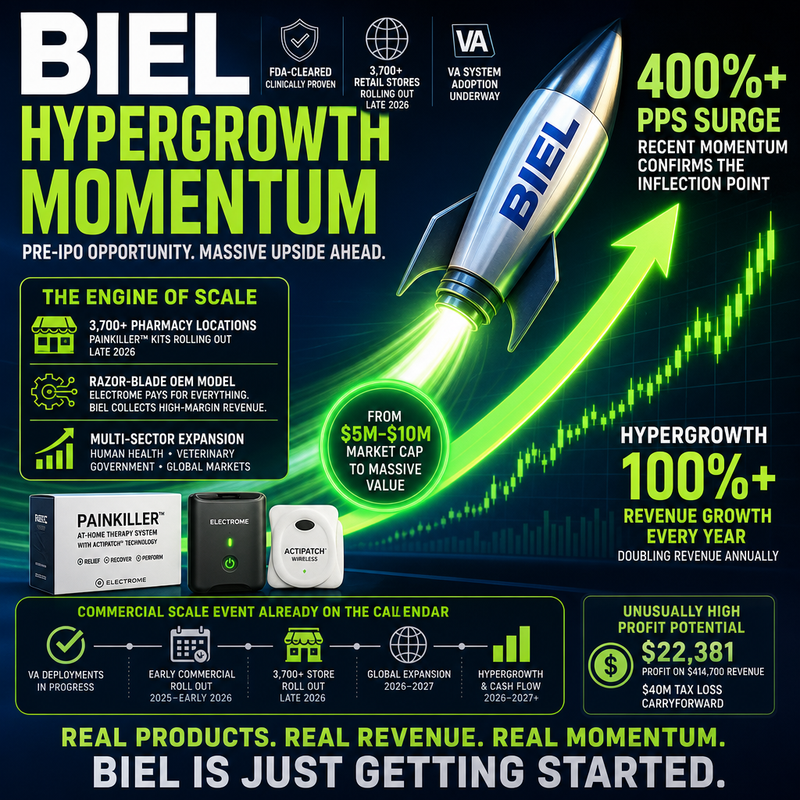
1. Seed-Stage Valuation for a Commercial-Stage Company
BIEL trades at a $5M–$10M market cap despite FDA-cleared products, global distribution, and a commercial partner scaling into thousands of locations — the exact asymmetric setup VCs hunt for.
2. FDA-Cleared, Clinically Proven Technology
ActiPatch® and RecoveryRx® have multiple FDA clearances, peer-reviewed studies, and real-world outcomes — including Stanford-supported arthritis data.
3. A Defensible Moat Built Over 30 Years
Patents, regulatory clearances, and decades of clinical data create a moat that would cost tens of millions to replicate.
4. Institutional Adoption Already Underway
BIEL hardware is entering the VA system, international markets, veterinary health, and 3,700 national pharmacy locations.
5. The 3,700-Store Retail Rollout (Late 2026)
Electrome cannot ship a single PAINKILLER™ unit without BIEL’s OEM module. The rollout triggers both pipeline fill and recurring restock revenue.
6. Razor-Blade OEM Revenue Model With Zero Scaling Costs
Electrome pays for marketing, distribution, retail slotting, and customer acquisition. BIEL simply collects OEM revenue.
7. A Commercial Timeline Already Lined Up Through 2027
VA deployments, early commercial rollout, 3,700-store onboarding, and global expansion create a multi-year revenue ramp.
8. Extreme Profitability Potential
BIEL historically converts revenue to profit at unusually high rates — including a $22,381 profit on $414,700 quarterly revenue (2021) supported by a $40M tax loss carryforward. Every $3M in revenue should generate about $2.5M profit.
9. A Clear PPS Ladder With Real Revenue Behind It
The modeled path:
$0.001 — Technical breakout (2026)
$0.01 — Cash-flow positive (2026)
$0.10 — Retail scale (2027)
$1.00 — Post-debt, buyback era (2028)
10. A True Pre-IPO Style VC Opportunity — Without Gatekeepers
Seed-stage valuation + FDA-cleared tech + institutional distribution + razor-blade revenue engine = a VC-grade setup available to retail.
11. Momentum Is Already Built In (Recent 400% PPS Surge)
The stock has already demonstrated explosive momentum with a 400% PPS surge, confirming market recognition of the inflection point.
12. Hypergrowth Trajectory: Revenues Doubling Every Year
The company is positioned for 100%+ revenue growth annually, driven by OEM demand, retail restocking, and multi-sector adoption.
13. AI Association: BIEL Is a Hardware Backbone for an AI-Native Therapeutics Platform
Electrome’s PAINKILLER™ platform — which requires BIEL hardware in every kit — is part of the AI-driven healthcare wave, one of the hottest sectors in the market.
14. Multi-Sector Expansion: Human, Veterinary, Government, Global Retail
BIEL isn’t a single-market story — it’s expanding across human health, veterinary medicine, government systems, and global retail simultaneously.
15. The Commercial Scale Event Is Already on the Calendar
Unlike speculative biotech or pre-revenue startups, BIEL has a scheduled, modeled, revenue-generating commercial event — the 3,700-store rollout — locked in.