.jpg)
5) Spanish Mountain Gold - Update (March 5) ..........................................
西班牙山黄金 - 运营更新
西班牙山黄金 - 運營更新
https://investorshangout.com/images/MYImages/...uction.jpg
Peter Mah of Spanish Mountain Gold Ltd. presents at Metals Investor Forum in Toronto | February 2026 (10 minutes)
https://www.youtube.com/watch?v=I2XVcbte6tU
Jason Dunning & Peter Mah of Spanish Mountain Gold talks to John Kaiser at the Metals Investor Forum 2026 (20 minutes)
https://www.youtube.com/watch?v=BgDAvF5cv9w
John Kaiser: "I like to finish off by saying that in my 40-year of career I have never seen a situation like today where the market is underpricing ounce in the ground gold project relative where gold price is. That my entire history has been, oh yeah, we are pricing for the future price of gold. Now we have the opposite and there's going be an inflection coming sometimes this year where people realize oh, the market has it wrong. So I am looking forward ......."
Peter Mah: 4 million ounces (gold), 5 million ounces (silver), 100 million market cap, hugely undervalued, great opportunity, can't agree anymore.
Biography of Jason Dunning
https://people.equilar.com/bio/person/jason-d...n/50679277
https://www.linkedin.com/in/jasondunning/
Biography of John Kaiser
https://cambridgehouse.com/u/2155/john-kaiser
===================
Latest News Release
===================
March 2, 2026 - Spanish Mountain Gold Receives Positive Particle Ore Sorting Results for the Phoenix Deposit Highlighting Production Upside
https://www.stockwatch.com/News/Item/Z-C!SPA-3791171/C/SPA
X-ray transmission (“XRT”) results based on the samples tested from the Phoenix deposit show an upgrade potential of two or more times the grade of the sample through a high mass rejection of waste and lower-grade material in the order of 50% to 70% of the feed mass. Particle ore sorting resulted 85% to 92% recovery of gold from the samples.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
February 27, 2026 - Spanish Mountain Gold Ltd. (the "Company" or "Spanish Mountain Gold" (TSX-V: SPA) (FSE: S3Y) (OTCQB: SPAUF) is pleased to announce that it has signed a Memorandum of Understanding (“MoU”) with Metso Canada Inc. (“Metso”), as it moves closer to advancing its Spanish Mountain Gold (“SMG”) project towards feasibility and permitting. The SMG project is located in the Cariboo District corridor in British Columbia, Canada.
https://www.stockwatch.com/News/Item/Z-C!SPA-3790618/C/SPA
=================================================================
Spanish Mountain Gold is inching towards Feasibility and Mine Building Decision
=================================================================
Metso Canada services (video)
https://www.youtube.com/watch?v=wgiF9uZqDsE
Metso website
https://www.metso.com/corporate/sustainabilit...-offering/
Metso Canada (formerly Metso Outotec) is a technology provider that supplies mining equipment such as crushers and grinding mills to various companies, including recent project like Blackwater Mine in the Cariboo region of British Columbia. It is a leading global industrial company and a frontrunner in sustainable technologies, end-to-end solutions and services for the aggregates, minerals processing and metals refining industries. They focus on improving their customers’ energy and water efficiency, increase their productivity and reduce environmental risks with their product. Crushing, screening and grinding is their core business.
Key Aspects of Metso’s Business:
Aggregates: Provides crushing and screening equipment (mobile and fixed) for quarrying and construction industries.
Minerals Processing: Offers technology for mining, including grinding mills, separation, filtration, and tailings management.
Metals Refining: Provides solutions for metal processing.
Services & Wears: Delivers a broad portfolio of aftermarket services, spare parts, and wear parts to optimize equipment performance.
Sustainability: Focuses on "Planet Positive" solutions aimed at reducing energy and water consumption in customer operations.
==========================================================================
Spanish Mountain Gold - Vision For The Future ( following the footsteps of Blackwater Mine )
==========================================================================
Blackwater Mine - Owned by Artemis Gold, located 250 kilometers northwest of Spanish Mountain Gold and 160 km southwest of Prince George
https://www.google.ca/maps/place/Blackwater+M...FQAw%3D%3D
Artemis Gold share price ( ARTG.V )
https://stockcharts.com/sc3/ui/?s=ARTG.V&...8838982129
Mine construction began in 2023 and completed after 22-month with gold/silver pouring starting in early 2025. As one of Canada's largest gold development projects, it is a 100% electrified facility designed to be a low-emission, open-pit mine. It officially opened on May 30, 2025.
Metso Canada (formerly Metso Outotec) delivered a Superior MK-III 4265 primary gyratory 18MW SAG mill crusher, a Nordberg HP900 cone crushers, and a 14MW ball mill to Blackwater Mine.
The equipment contract was facilitated through Sedgman Canada Limited, which is managing the engineering, procurement, and construction.
Subsequent wet plant (milling and CIL circuit) transitioned the operation from construction to production.
The site features a fully electrified processing facility, a 225kV transmission line, and a significant tailings storage facility.
The project employs over 400 people, with a high percentage of local and Indigenous representation.
In December 2025 Artemis Gold approved a $1.44 billion Phase 2 expansion to increase production. Construction is planned for Q3 2026 and completion is expected in Q3 2028. The expansion aims to boost processing capacity, positioning it among Canada's largest gold mines.
Designed with a low carbon footprint, replacing traditional fuels with electric equipment for mining and processing.
It is an open pit gold and silver mine with mine life of 22 year and with mill throughput of 16,000 tpd, expandable to 33,000 tpd in year 6 and 55,000 tpd in year 11. It has Proven Reserves of 8 million ounces of gold, 62.2 million ounces of silver and Probable Resources of 11.7 million ounce of gold, 122.4 million ounces of silver.
=================================
Blackwater Mine - Capital Expenditure
================================
The initial capital expenditure (CAPEX) for Phase 1 of the Blackwater Mine in British Columbia, Canada, was guided to be between C$730 million and C$750 million. As of December 31, 2023, approximately C$389 million of this initial capital had been spent, with 84% of the lower end of the guided range (C$615 million) contractually committed.
Remaining Capex: As of March 31, 2024, remaining Phase 1 capital expenditures were estimated at C$207 to C$227 million.
Scope: Phase 1 focused on building an open-pit mine and a processing facility with a capacity of 6 million tonnes per annum (Mtpa).
Subsequent Phase 1 Upgrades ("Phase 1A"
In September 2025, Artemis Gold announced plans to upgrade the Phase 1 processing plant (dubbed Phase 1A), aiming to increase capacity from 6 Mtpa to 8 Mtpa by Q4 2026.
Phase 1A Capital Cost: Estimated at C$100–C$110 million, to be funded by operating cash flows.
Goal: To increase throughput and efficiency while leveraging the existing team that built Phase 1.
Artemis Gold's Phase 2 (EP2) expansion of the Blackwater mine in B.C. is estimated to cost $1.44 billion CAD, designed to expand processing capacity to 21 Mtpa. Expected to be completed around 2028, this expansion will be funded primarily through operating cash flows, aiming to produce over 500,000 ounces of gold annually.
==============================================
Blackwater Mine - Average gold grade and silver grade
==============================================
First 5 Years: Averaging 1.29 g/t gold.
Subsequent 17 years: Average 0.75 g/t gold.
Silver Grade: The average silver grade is estimated to be 5.78 g/t Ag over the life of the mine.
Reserve Basis: Total proven and probable reserves are estimated at 334.3 million tonnes at 0.75 g/t gold with gold content of 8 million ounces and 5.8 g/t silver with silver content of 62 million ounces.
First 5 years average annual production: 463,000 ounces of gold and 1.9 million ounces of silver.
==============================
Blackwater Mine construction videos
=============================
1) Feb 2025 - Aerial tour
https://www.youtube.com/watch?v=ndcRuX42b3U
2) Feb 2025 - Mining Technology
https://www.youtube.com/watch?v=8WfAvX_Nzb4
3) Feb 2025 - Health and Safety
https://www.youtube.com/watch?v=ELbEBpNQMAw
4) Feb 2025 - Completion of construction
https://www.youtube.com/watch?v=fpl3Vjd9slM
5) April 2025 - First gold pouring occurred in January 2025
https://www.youtube.com/watch?v=E9nFlVjKIe4
6 May 30, 2025 - Opening ceremony
https://www.youtube.com/watch?v=MOXjjZcGdYw
7) Dec 2025 - Phase 2: Production Expansion
https://www.youtube.com/watch?v=R7xr4kidz4I
==============================================================
Spanish Mountain Gold - Vision for the future through the life of Gibraltar Mines
==============================================================
https://www.youtube.com/watch?v=yJmanh1uQMQ
Gibraltar Mines - Owned by Taseko Mines, located 50 kilometers west of Spanish Mountain Gold
https://www.google.ca/maps/place/Gibraltar+Mi...FQAw%3D%3D
The Gibraltar Mine is the second-largest open-pit copper-molybdenum mine in Canada, owned and operated by Taseko Mines. Its primary resource is low-grade porphyry copper-molybdenum deposit containing minerals chalcopyrite, molybdenite, bornite, and cuprite. As of December 31, 2024, the mine has 616 million tons of 0.26% copper and 0.008% molybdenum.
https://stockcharts.com/sc3/ui/?s=TKO.TO&...5512188236
===================
Corporate Presentation
===================
https://spanishmountaingold.com/investors/presentations/
===============
Operation Update
===============
The 2024 and 2025 exploration drill program identified opportunities to improve the average grade of the mineral resources and potentially grow the in-pit and near pit resources.
The Company’s current strategy remains focused on optimizing, de-risking and advancing its Spanish Mountain Gold Project towards a build decision in 2026.
The company has commenced a particle ore sorting program with ABH Engineering Inc. and a bulk ore sorting study with OrePortal Technologies Ltd.
If the XRT ore sorting program will be successfully implemented, capital expenditure will be reduced while future gold productivity will increase.
On August 27, 2025 the company closed the $7,199,968 equity financing. ( https://spanishmountaingold.com/news/2025/spa...placement/ ). The fund will be sufficient to fund the Fall drill program, feasibility study and ore sorting program till 2026. According to CEO Peter Mah, future financing will employ non-dilutive approach.
Warrant Financing: The exercise of 25 cents and 18 cents outstanding warrants expiring on May 30 and November 15 of 2026 respectively will bring C$10.9 million into the treasury in 2026, helping to fund the project's progression.
Excerpt from the May 31,2024 financing: "The 25 cent warrants will expire on May 30, 2026. Each Warrant entitles the holder thereof to purchase one additional Share (a “Warrant Share”) at a price of $0.25 per Warrant Share for a period of 24 months from the date of issuance, subject to earlier expiry if the 10-day volume weighted average price of the Common Shares on the TSX Venture Exchange (the “TSXV”) exceeds $0.30 per Common Share".
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...3-million/
The company has engaged the services of Atrium Research Corporation, a leading company sponsored research firm. Atrium will produce a range of research services to the Company and present the Company’s investment case to potential investors. Atrium will also host video interviews with the Company’s management team to present the investment case in an interview format.
Atrium Research increased SPA.V price target to $0.80
https://www.atriumresearch.ca/spa
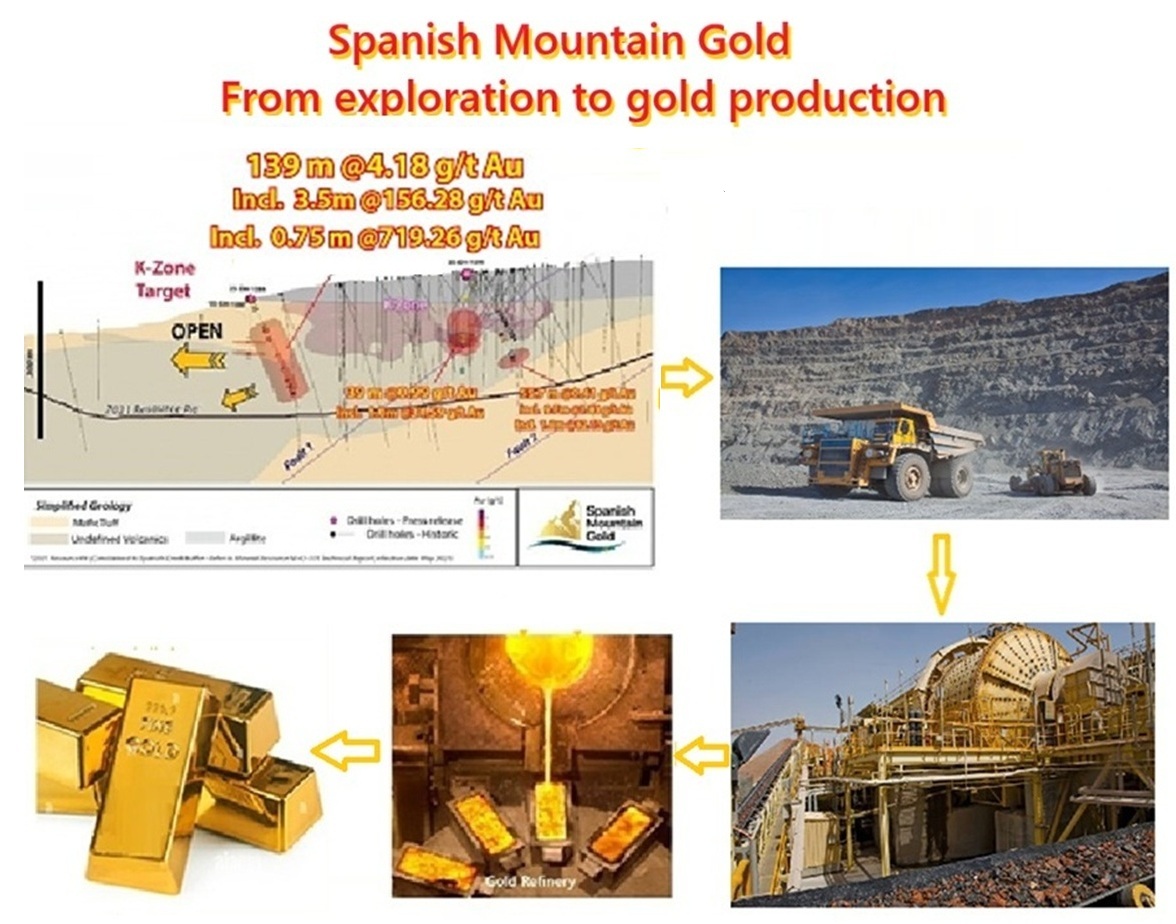
Current exploration drilling assay results continues to intersect significant higher-grade mineralization over 300 m in strike length in the newly defined Orca Fault target and the continuity can now be traced across two parallel, adjacent drill sections. The deep intersection in drill hole 25-DH-1299, grading 1.67 g/t gold over 45.54 m confirms historical drilling that there is higher-grade mineralization at depth and additional drilling is required to quantify the deeper mineral potential.
The completion of the Preliminary Economic Assessment and NI-43-101 Technical Report on July 3, 2025 will form the basis for a new PEA and new MRE in 2026 after additional gold resources is delineated into the in pit operation from the high grade K-zone and Phoenix zone. The Company will begin a new Pre-Feasibility Study (PFS) or potentially advancing directly to a Feasibility Study (“FS”).
=============
Future Prospect
=============
Spanish Mountain Gold's market capitalization is well below its peer. With analysts providing price targets suggesting it is undervalued, potentially offering significant growth. The company's undervaluation stems from factors like a pending resource update, potential high-grade discoveries, and a unique "green gold" opportunity from available hydroelectric power.
Upcoming Catalyst: A new preliminary economic assessment and new resource estimate are expected to re-evaluate the stock's price.
Mineralization Potential: The project has high-grade mineralization across a significant length, suggesting the potential for future discoveries.
Green Gold Opportunity: The company's access to clean hydroelectric power presents a unique "green gold" investment prospect.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

CFO Mark Ruus presents Spanish Mountain Gold at VRIC on January 26, 2026 (Duration: 13 minutes)
https://www.youtube.com/watch?v=YzmLGz1Xhhg
Mark Ruus, Chief Financial Officer of Spanish Mountain Gold
Mr. Ruus brings nearly three decades in the mining sector. He began his career at PwC and has since progressed to Vice President and Senior Vice President Tax positions at leading gold mining firms like Kinross Gold Corporation, Goldcorp Inc., and Placer Dome Inc. His experience and CPA - CA qualification underpin his extensive knowledge in financing, cost control, business efficiency, compliance, tax issues, mergers and acquisitions, and financial reporting for domestic and global mining companies.
============================================================================================
Spanish Mountain Gold's Strategic Shift: Auditor Change and Leadership Transition as Catalysts for Growth in 2026
============================================================================================
- Spanish Mountain Gold replaces auditor and appoints new finance director to strengthen governance for 2027 construction decision.
- New auditor BDO and Kim Leroux’s expertise aim to enhance financial oversight and First Nations engagement in British Columbia.
- Operational readiness includes updated resource estimates, 2025 drilling, and XRT technology to optimize gold recovery and reduce carbon footprint.
- Strategic moves address governance risks and sustainability trends, positioning the company to navigate regulatory and market challenges.
The mining sector's transition from exploration to development-stage projects demands robust corporate governance and operational readiness. For Spanish Mountain Gold Ltd., a junior explorer aiming to evolve into an emerging developer, recent strategic moves-namely, a change in auditors and a leadership transition-signal a deliberate effort to align governance and technical capabilities with its 2027 construction decision timeline. These changes, coupled with operational advancements, position the company to navigate the complexities of project development in a resource-constrained and increasingly sustainability-focused industry.
Auditor Change: Strengthening Governance for Development-Stage Rigor
Spanish Mountain Gold's decision to replace Smythe LLP with BDO LLP as its auditor reflects a strategic pivot toward enhanced financial oversight and credibility. According to a report by Business Wire, the Audit Committee selected BDO for its "extensive experience working with mining companies," a critical factor as the firm advances its Spanish Mountain Gold Project toward a build decision. This shift underscores the company's recognition that development-stage projects require auditors with sector-specific expertise to navigate regulatory scrutiny and investor expectations.
The transition also highlights the importance of transparency in capital markets. By filing a Notice of Change of Auditor along with required letters from both the former and successor auditors on SEDAR+, Spanish Mountain Gold has demonstrated compliance with Canadian securities regulations. For investors, this move reduces governance risks associated with inexperienced auditors, a concern that has historically plagued junior miners. BDO's track record in mining audits may also facilitate smoother interactions with lenders and partners, who often demand rigorous financial due diligence before committing to large-scale projects.
Leadership Transition: Kim Leroux's Appointment as a Governance Win
Complementing the auditor change is the appointment of Kim Leroux as Director Finance, effective January 2, 2026. Leroux's background spanning roles at DeBeers and McEwen Mining Inc.-brings a depth of mining finance expertise that aligns with the company's operational ambitions. Notably, her experience in First Nations relationship management adds a critical dimension to corporate governance, particularly in British Columbia, where community engagement is pivotal to project permitting and social license to operate.
The transition from part-time contract CFO Mathew Lee to Leroux's full-time leadership role also addresses a common vulnerability in junior mining firms: inconsistent financial stewardship. By ensuring a seamless handover during Q1 2026, the company minimizes operational disruption while positioning itself to manage the capital-intensive phases of feasibility studies and infrastructure planning. Leroux's focus on "developing and implementing processes and systems" suggests a governance-driven approach to scaling operations, which is essential for attracting institutional investment.
Operational Readiness: Technical and Sustainability-Driven Progress
Beyond governance, Spanish Mountain Gold's operational readiness measures are equally compelling. The completion of a new Mineral Resource Estimate (MRE) and Preliminary Economic Assessment (PEA) by July 2025 provides a data-driven foundation for subsequent feasibility studies. These studies, combined with a 2025 exploration drill program targeting 10,000 meters, aim to de-risk the project by extending mineralization at key targets like Phoenix and K-zone.
Innovation in processing technology further strengthens the company's development-stage preparedness. The exploration of X-ray transmission (XRT) ore sorting-a technique to enhance gold recovery-demonstrates a proactive approach to optimizing project economics according to a Financial Post report. Simultaneously, collaborations with BC Hydro to integrate renewable diesel and electrification initiatives highlight a commitment to reducing the project's carbon footprint, a growing priority for ESG-focused investors. These efforts align with global trends toward decarbonization in mining, potentially improving the project's long-term viability in a regulatory and market landscape increasingly shaped by sustainability metrics.
Strategic Alignment and Future Outlook
Spanish Mountain Gold's dual focus on governance and operational readiness creates a synergistic foundation for its 2027 construction decision. The auditor change and leadership transition address internal capacity constraints, while technical advancements and sustainability initiatives tackle external challenges such as permitting delays and capital cost inflation. For development-stage miners, these factors are often the difference between project success and stagnation.
However, risks remain. The 2025 drill program's results will be critical in validating the MRE's assumptions, and delays in feasibility studies could push the construction decision beyond 2027. Additionally, Leroux's ability to integrate First Nations partnerships into the project's governance framework will determine the speed of regulatory approvals. Investors must monitor these milestones closely, but the company's current trajectory suggests a well-structured path to becoming a producer.
Conclusion
Spanish Mountain Gold's strategic shift in 2026-from auditor and leadership changes to operational innovations-exemplifies how development-stage mining firms can mitigate risks and enhance value. By prioritizing governance rigor and technical preparedness, the company is positioning itself to capitalize on the gold sector's long-term fundamentals while addressing the ESG imperatives of modern capital markets. For investors, the question is no longer whether the project can advance, but how swiftly it can execute its ambitious timeline.
News reference
https://spanishmountaingold.com/news/2025/spa...scal-2025/
==================================
Warrants, Options, Insider share ownership
==================================

https://investorshangout.com/images/MYImages/...302026.jpg
Insider trading transaction record
https://www.barchart.com/stocks/quotes/SPA.VN/insider-trades
https://www.canadianinsider.com/company-insid...cker=SPA.V
==========================================
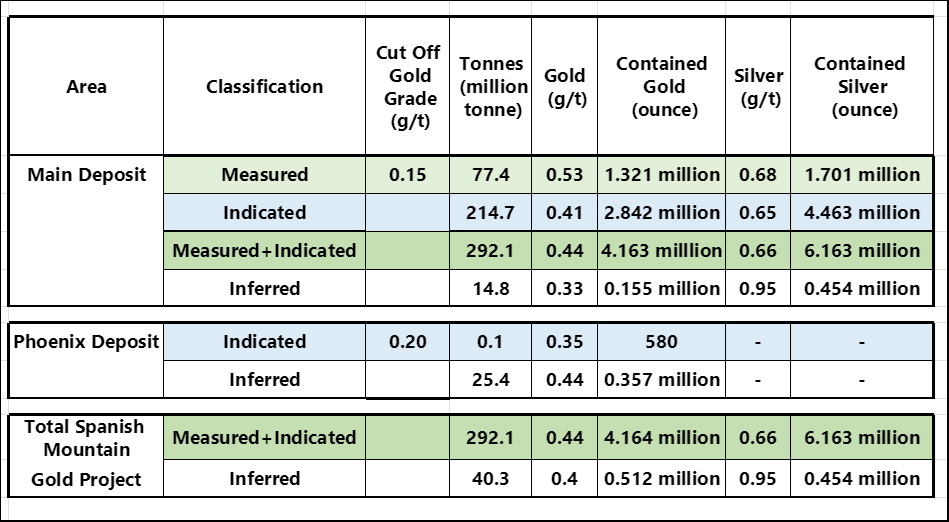
Mineral Resource Estimate (MRE) as of July 3, 2025
==========================================
https://investorshangout.com/images/MYImages/...timate.png
Resources in the high grade K-zones are not included in the July 3 PEA.
======================================
Unofficial gold resources estimate in the K-zone
======================================
As of February 26,2026

https://investorshangout.com/images/MYImages/...K-zone.jpg
Drilling area:

https://investorshangout.com/images/MYImages/...argets.png
Based on the updated assays in the K-zone and based on the silver resource to gold resource ratio of 1.5 in the Main Zone, if the tonnage in the K-zone is at least 200 million tonnes as in the Main zone, K-zone will has Measured + Indicated resources of 5 million ounces gold and 7 million ounces silver added to the July 3, 2025 PEA.
2026 new PEA's new MRE will show gold and silver Measured + Indicated resources (Proven Reserve) of 9 million ounces of gold and 13 million ounces of silver. If it will be a reality, share price will be very explosive.
2025 drilling consistently intersecting long intervals of high grade gold could be an indication that they are drilling close to the network of gold veins where the placer gold originated as some of the gold veins disintegrated and the gold fragments corroded into fine placer gold by weathering over millions of years. There could still be intact gold veins in SMG's 135 square kilometer property to be discovered. Including the high grade gold in future PEA will significantly reduce capital expenditure and increase gold productivity.
The term "high grade" is relative to the deposit style. The Spanish Mountain project is primarily a large-scale, open-pit, bulk-tonnage project, where the average grades are generally lower compared to narrow-vein underground mines. In this context, grades approaching or exceeding 1 g/t over significant widths are considered "higher-grade" and economically significant for the project's development, especially for the early years of the mine life. The company is also investigating ore sorting technology to potentially increase the processed grade and enhance project economics.
==================================
Charts - Gold, Silver, XAU, SPA.V, SPAUF
==================================
Gold Price - weekly (price updated at End Of Day)
https://stockcharts.com/h-sc/ui?s=$GOLD&p...e_vignette
50-year gold price
https://mrci.com/pdf/gc.pdf
Silver Price - weekly (price updated at End Of Day)
https://stockcharts.com/h-sc/ui?s=$SILVER&...e_vignette
50-year silver price (price in cents)
https://mrci.com/pdf/si.pdf
XAU weekly
https://stockcharts.com/h-sc/ui?s=%24XAU&...9099899440
SPA.V weekly
https://stockcharts.com/h-sc/ui?s=SPA.V&p...e_vignette
SPA.V News, trade data
https://www.stockwatch.com/Quote/Detail.aspx?C:SPA.V
SPAUF.OTCQB weekly
https://stockcharts.com/sc3/ui/?s=SPAUF&p...e_vignette
SPAUF Level 2
https://www.otcmarkets.com/stock/SPAUF/overview
S3Y.FSE
https://ca.finance.yahoo.com/quote/S3Y.F/char...NlcyI6e319
===============
Technical Analysis
===============

https://investorshangout.com/images/MYImages/...SPA.VM.jpg

https://investorshangout.com/images/MYImages/...alysis.png

https://investorshangout.com/images/MYImages/...alysis.png
SPA.V weekly
https://stockcharts.com/sc3/ui/?s=SPA.V&p...8609492691
Case history of bullish Head & Shoulder
BullishHead&Shoulderpatternscasehistory.png)
https://investorshangout.com/images/MYImages/...istory.png
====================================
Production infrastructure build financing plans
====================================
Gold price

OPTION 1 - Joint venture with a cash rich mining company
OPTION 2A - Debt financing (With XRT ore sorting technology)

https://investorshangout.com/images/MYImages/...ology).jpg
OPTION 2B - Debt financing (No XRT ore sorting technology, process all rocks)

https://investorshangout.com/images/MYImages/...ology).jpg
OPTION 3 - Buyout deal
========================================
Historical buyout deals in the Golden Triangle, BC
========================================
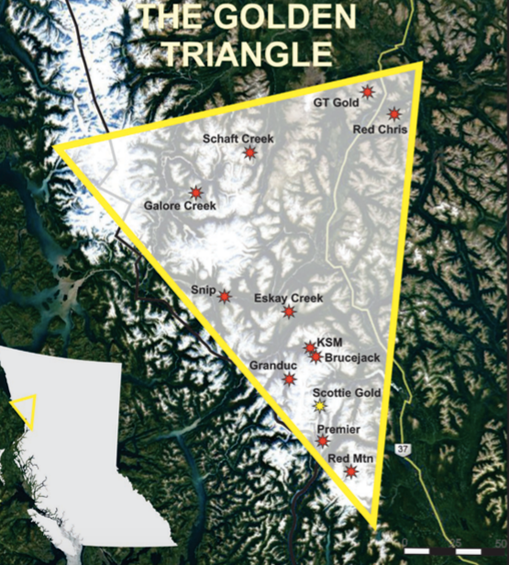
Placer Dome and International Corona acquired Stikine Resources at Can$67 per share
https://www.northernminer.com/news/placer-sta...000178407/
Imperial Metals acquired American Bullion Minerals Ltd. at Can$2.45 a share
https://imperialmetals.com/for-our-shareholde...an-bullion
Newmont acquired GT Gold at $3.25 per share in a Can$393 million deal
https://www.newmont.com/investors/news-releas...fault.aspx
Australian gold and copper producer Newcrest Mining acquired Pretium Resources in a Can$3.84 billion, $18.5 per share deal
https://magazine.cim.org/en/news/2021/newcres...e%20region
In Ontario, Kinross acquired Great Bear Resources for $32 a share in the $1.8 billion deal
https://www.globalminingreview.com/finance-bu...resources/
====================================================
Preliminary Economic Assessment and NI-43-101 Technical Report
====================================================
https://investorshangout.com/images/MYImages/...67_PEA.png
Preliminary Economic Assessment Economics
https://spanishmountaingold.com/project/preli...economics/
August 18, 2025 - NI-43-101 Technical Report
https://spanishmountaingold.com/site/assets/f...-final.pdf
===================================
All-In-Sustaining-Cost of 25 gold producers
===================================
https://www.mining.com/wp-content/uploads/202...31425A.gif
What is All In Sustaining Costs (AISC)?
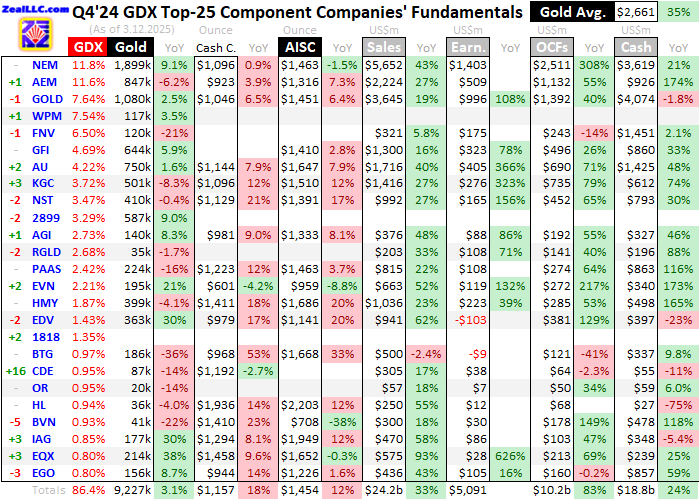
All-in Sustaining Costs (AISC) in the mining industry, particularly for gold, includes all operating costs, sustaining capital expenditures, and other costs associated with maintaining current production. This includes cash costs, sustaining capital expenditures, general and administrative (G&A) expenses, and environmental and closure costs.
Breakdown on AISC:
Cash Costs:
These are the direct costs of mining and processing, including labor, energy, consumables, and royalties (net of by-product credits).
Sustaining Capital Expenditures:
These are investments required to maintain current production levels, such as equipment replacement, mine development, and other costs to keep the mine operating at its current capacity.
General and Administrative (G&A) Expenses:
These are the costs associated with running the corporate office and other administrative functions that support the mine's operations.
Environmental and Closure Costs:
These include costs related to environmental remediation and mine closure, such as reclamation and decommissioning.
Exploration Expenses (Sustaining):
These are exploration costs that are needed to maintain current production levels and replace depleted resources.
AISC is a comprehensive metric designed to provide a more complete picture of the total cost of mining an ounce of gold, beyond just the direct cash costs.
===============================
Key Steps Leading to a Build Decision
===============================
Spanish Mountain Gold has indicated that production infrastructure construction decision will be made in 2026, after which a two-year construction phase will begin. This timeline allows for the completion of the ongoing drill program, a new Mineral Resource Estimate (MRE) and a new Preliminary Economic Assessment (PEA) in the second half of 2026, as well as securing all necessary reports and approvals to advance development of the project. The new PEA and MRE are crucial steps in optimizing the project for construction. Completing all technical reports and regulatory approvals is a necessary part of the process before the build decision can be made.
========
Overview
========
A mining project can pay loans before achieving revenue by using alternative financing like stream financing, royalty financing, or joint ventures, which are less restrictive than traditional debt and use future production or revenue as collateral instead of pre-existing income. Other methods include securing government grants and incentives, pre-selling a portion of future production through off-take agreements, and raising equity capital through share issues.
===========================
Pre-Revenue Financing Methods
===========================
Streaming Agreements: A company provides upfront capital in exchange for a percentage of the mine's future mineral production, often at a discounted price, according to Stikeman Elliott.
Royalty Financing: A financier funds a project in return for a share of the project's future revenue or profits, which can be seen as an endorsement of the project's potential, says Stikeman Elliott and Lexology.
Joint Ventures: Partnering with other mining companies or investors allows costs to be shared, spreading the financial burden, notes www.altfin.net.
Off-take Agreements: Pre-selling a portion of the future mineral output to buyers can secure upfront financing and provide lenders with confidence in the project's potential.
Government Funding: Governments and development banks sometimes offer grants, loans, or tax incentives for projects aligned with economic or environmental goals, according to www.altfin.net.
Equity Financing: Raising capital by issuing shares is often considered the simplest path for early-stage projects, as it avoids the complexities and strict requirements of debt financing.
Benefits of These Approaches
Non-Dilutive (for streams/royalties): These options don't dilute the original shareholders' equity in the company, notes Stikeman Elliott.
Flexible Terms: Stream and royalty structures can be more flexible and less restrictive than traditional bank debt, allowing for customized repayment profiles, according to Appian Capital Advisory LLP.
Market Confidence: Agreements like streaming and royalties can be seen as a market endorsement of the project, potentially leading to increased investor confidence.
===================
Promise for profitability
===================
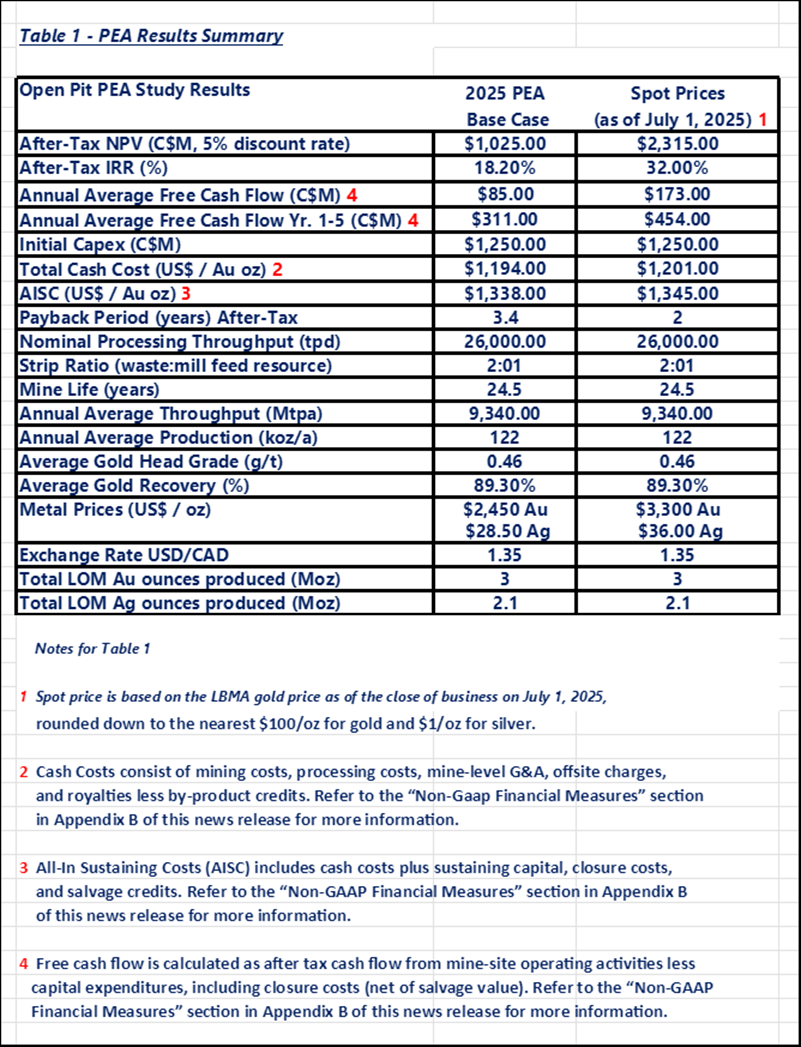
Spanish Mountain Gold shows promise for profitability due to a recently updated Preliminary Economic Assessment (PEA) indicating strong economics with a base case NPV5% of C$1.0 billion and an IRR of 18.2%, potentially improving to C$2.3 billion NPV5% and 32.0% IRR with higher gold prices. The project's conventional open-pit, milling operation, access to infrastructure, and new management team with experience in construction and operations contribute to its potential success, although the company is still in the early development stages.
Factors supporting profitability:
Favorable Economics: The PEA projects significant financial returns, with an after-tax Net Present Value (NPV) of C$1.0 billion and an Internal Rate of Return (IRR) of 18.2% at a base gold price of US$2,450/oz, and even better results at a spot price of US$3,300/oz gold.
Strong Resource Confidence: The economic analysis is based on a high degree of resource confidence, incorporating measured and indicated resources, which are key to a successful mining project.
Experienced Management: A new board and management team, brought in since 2022, possess decades of experience in project management, construction, and operations, positioning the company for a production decision.
Developed Infrastructure: The project will benefit from established infrastructure in central British Columbia, including road access and proximity to the city of Williams Lake, reducing operational complexities and costs.
Strategic Project Design: The company plans a conventional open-pit and milling operation, which is a low-risk approach that is less complex than underground mining.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
https://investorshangout.com/images/MYImages/...uction.jpg
簡體中文
==============
最新消息发布
=============
2026年3月2日 - 西班牙山黄金 Phoenix 矿床颗粒矿石分选结果积极,凸显产量提升潜力
https://www.stockwatch.com/News/Item/Z-C!SPA-3791171/C/SPA
基于 Phoenix 矿床样品测试的X射线透射(XRT)结果显示,通过大量剔除废料和低品位矿石(约占进料质量的50%至70%),矿石品位有望提升至样品品位的两倍甚至更高。颗粒矿石分选后,样品中黄金的回收率达到85%至92%。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
2026年2月27日 - 西班牙山黄金 (TSX-V: SPA)(FSE: S3Y)(OTCQB: SPAUF)欣然宣布已与 Metso Canada Inc.(“Metso”)签署了一份谅解备忘录(“MoU”),该公司正朝着推进其西班牙山金矿(“SMG”)项目的可行性和许可迈进。 SMG项目位于加拿大不列颠哥伦比亚省的卡里布区走廊。
https://www.stockwatch.com/News/Item/Z-C!SPA-3790618/C/SPA
==========================================
西班牙山黄金 正在逐步接近可行性和矿山建设决策
==========================================
Metso Canada 服务(视频)
https://www.youtube.com/watch?v=wgiF9uZqDsE
https://www.metso.com/corporate/sustainabilit...-offering/
Metso Canada(前称Metso Outotec) 是一家技术供应商,为提供多家公司采矿设备例如破碎机和磨机, 包括位于 British Columbia Cariboo 地区 的 Blackwater Mine。作为一家全球领先的工业公司,美卓在骨料、矿物加工和金属精炼行业的可持续技术、端到端解决方案和服务方面处于领先地位。该公司致力于通过其产品提高客户的能源和水资源利用效率,提升生产率并降低环境风险。破碎、筛分和研磨是其核心业务。
Metso业务的关键方面:
骨料:为采石和建筑行业提供破碎和筛分设备(移动和固定)。
矿物加工:提供采矿技术,包括磨矿机、分离、过滤和尾矿管理。
金属精炼:提供金属加工解决方案。
服务与磨损件:提供广泛的售后服务、备件和磨损件,以优化设备性能。
可持续性:专注于“积极地球”解决方案,旨在减少客户运营中的能源和水消耗。
==============================================
西班牙山黄金 -- 展望未来 ( 追随Blackwater Mine 的足迹 )
==============================================
Blackwater Mine - Artemis Gold 拥有,位于西班牙山黄金 以西250公里,Prince George 以西南160公里。
https://www.google.ca/maps/place/Blackwater+M...FQAw%3D%3D
Artemis Gold 股价 (ARTG.V)
https://stockcharts.com/sc3/ui/?s=ARTG.V&...8838982129
矿山建设于2023年开始,并在22个月后完成,金银冶炼将在2025年初开始。 作为加拿大最大的黄金开发项目之一,它是一个100%电气化的设施,旨在成为一个低排放的露天矿。 它于2025年5月30日正式开业。
Metso(前身为Metso Outotec)交付了一台Superior MK-III 4265初级旋回破碎机、Nordberg HP900圆锥破碎机和一台14MW球磨机。
设备合同是通过Sedgman Canada Limited促成的,该公司负责工程、采购和施工的管理。
随后的湿法厂(磨矿和CIL工艺)将运营从建设阶段转变为生产阶段。
该地点设有一个完全电气化的加工设施、一条225千伏的输电线和一个重要的尾矿储存设施。
该项目雇用了超过400人,其中有很高比例的本地和土著代表。
2025年12月,阿尔忒弥斯黄金公司批准了一项14.4亿美元的二期扩建计划,以增加产量。 建设计划在2026年第三季度开始,预计在2028年第三季度完成。 扩建旨在提高加工能力,使其跻身加拿大最大的金矿之列。
设计时考虑了低碳足迹,用电动设备替代传统燃料进行采矿和加工。
这是一个露天金银矿,矿山寿命为22年,矿厂处理量为每天16,000吨,6年后可扩展至每天33,000吨,11年后可扩展至每天55,000吨。 它拥有800万盎司的黄金、6220万盎司的白银的探明储量,以及1170万盎司的黄金、1.224亿盎司的白银的可能资源。
=======================
Blackwater Mne - 资本支出
=======================
加拿大 British Columbia 的 Blackwater Mine 第一阶段的初始资本支出(CAPEX)预计在 $730 million 加元 至 $750 million 加元之间。 截至2023年12月31日,约 $389 million 加元的初始资本已被支出,其中 84% 的指导范围下限($615 million 加元)已合同承诺。
剩余资本支出: 截至2024年3月31日,第一阶段剩余的资本支出估计在 $207 million 至 227 million 加元之间。
范围:第一阶段集中于建设一个露天矿和一个年处理能力为 6 million 吨的加工设施。
后续第一阶段升级(“第一阶段A”)
2025年9月,Artemis Gold宣布计划升级第一阶段处理厂(称为第一阶段A),目标是在2026年第四季度之前将产能从每年 6 million 吨提高到 8 million 吨。
第一阶段A资本成本:估计为 $100 million 至 $110 million 加元,由运营现金流资助。
目标:在利用建设第一阶段的现有团队的同时,提高产量和效率。
Artmis Gold 的 Blackwater Mine 第二阶段(EP2)扩建预计将耗资 $1.44 billion 加元,旨在将处理能力扩展到每年 21 million 吨。 预计将在2028年左右完成,这一扩展将主要通过运营现金流来资助,目标是每年生产超过 500,000 盎司的黄金。
================================
Blackwater Mine - 平均金品位和银品位
================================
前五年:平均金品位 1.29 克/吨。
后十七年:平均金品位 0.75 克/吨。
银品位:预计矿山寿命期内平均银品位为 5.78 克/吨。
储量:探明和概略储量总计估计为 334.3 million 吨,金品位 0.75 克/吨,含金量 8 million 盎司;银品位 5.8 克/吨,含银量 62 million 盎司。
前五年平均年产量:黄金 463,000 盎司,白银 1.9 million 盎司
Blackwater Mine 建设视频
1) 2025年2月 - 空中巡游
https://www.youtube.com/watch?v=ndcRuX42b3U
2) 2025年2月 - 矿业技术
https://www.youtube.com/watch?v=8WfAvX_Nzb4
3) 2025年2月 - 健康与安全
https://www.youtube.com/watch?v=ELbEBpNQMAw
4) 2025年2月 - 完工
https://www.youtube.com/watch?v=fpl3Vjd9slM
5) 2025年4月 - 首次黄金浇铸于2025年1月进行
https://www.youtube.com/watch?v=E9nFlVjKIe4
6) 2025年5月30日 - 开幕式
https://www.youtube.com/watch?v=MOXjjZcGdYw
7) 2025年12月 - 第二阶段:生产扩展
https://www.youtube.com/watch?v=R7xr4kidz4I
===========================================
西班牙山黄金 - 通过 Gibraltar Mines 的一生未来展望
===========================================
https://www.youtube.com/watch?v=yJmanh1uQMQ
Gibraltar Mines - 隶属于 Taseko Mines, 位于西班牙山金矿以西50公里处
https://www.google.ca/maps/place/Gibraltar+Mi...FQAw%3D%3D
Gibraltar Mines 是加拿大第二大露天铜钼矿,其主要资源为低品位斑岩型铜钼矿床,矿物成分包括黄铜矿、辉钼矿、斑铜矿和赤铜矿。截至2024年12月31日,该矿拥有6.16亿吨矿石,铜品位为0.26%,钼品位为0.008%。
https://stockcharts.com/sc3/ui/?s=TKO.TO&...5512188236
=========
公司介绍
=========
https://spanishmountaingold.com/investors/presentations/
=====================
西班牙山黄金 - 运营更新
=====================
2024年和2025年的勘探钻探计划发现了提高矿产资源平均品位并可能增加矿坑内及附近资源量的机会。
公司目前的战略重点仍然是优化、降低风险并推进其西班牙山金矿项目,力争在 2027 年底前做出建设决策。
公司已与 ABH Engineering Inc. 合作启动颗粒矿石分选项目,并与 OrePortal Technologies Ltd. 合作开展散装矿石分选研究。
如果 XRT 矿石分选项目成功实施,资本支出将减少,而未来的黄金产量将提高。
2025年8月27日,该公司完成了 $7,199,968 的股权融资。 ( https://spanishmountaingold.com/news/2025/spa...placement/ ). 这笔资金足以支持秋季钻探计划、可行性研究和矿石分选计划,直至2026年。首席执行官彼得·马赫表示,未来的融资将采用非稀释性方式。
认股权证融资:行使面值分别为 $0.25 和 $0.18 的未行使认股权证(分别于 2026 5月31日 和 11月15日 到期)将在 2026 年为国库带来 $10.9 million,有助于资助该项目的进展。
摘自2024年5月31日的融资协议:“每股面值 $0.25 的认股权证将于2026年5月30日到期。每份认股权证赋予持有人自发行之日起24个月内以每股 $0.25 的价格购买一股额外股份(“认股权证股份”)的权利,但如果10日成交量加权平均价格超过每股 $0.30,则认股权证提前到期"。
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...3-million/
公司已聘请领先的企业赞助研究公司 Atrium Research Corporation 提供服务。Atrium 将为公司提供一系列研究服务,并向潜在投资者介绍公司的投资价值。Atrium 还将安排公司管理团队接受视频采访,以访谈形式阐述投资价值。
Atrium Research 将 SPA.V 的目标股价上调至 $0.80
https://www.atriumresearch.ca/spa
目前的勘探鑽探化驗結果持續顯示,在新劃定的 Orca 斷層靶區內,沿走向長度超過300公尺處存在顯著的高品位礦化,且該礦化帶已在兩個平行相鄰的鑽孔剖面上連續延伸。鑽孔 25-DH-1299 的深部交匯處,金品位為 1.67 克/噸,厚度為 45.54 米,位於 2025 年礦產資源估算 (MRE) 的約束露天礦坑邊界之下,證實了歷史鑽探結果,即深處存在更高品位的礦產化,並強調需要進行更深層的探礦潛力。
2025年7月3日完成的初步经济评估和NI-43-101技术报告将为2026年开展新的初步经济评估和矿产资源评估奠定基础。届时,将在高品位K区和凤凰区探明更多金矿资源后,启动露天矿坑作业。公司将启动新的预可行性研究(PFS),或可能直接进入可行性研究(FS)。
==========
未来展望
==========
西班牙山黄金 市值远低于同行。分析师给出的目标价表明该公司被低估,具有巨大的增长潜力, 原因包括即将发布的资源量更新报告、潜在的高品位矿藏发现,以及利用现有水力发电资源开发独特的“绿色黄金”机遇。
即将到来的催化剂:新的初步经济评估和资源估算预计将重新评估该股的价格。
矿化潜力:该项目拥有覆盖广泛、品位高的矿化带,表明未来存在发现金矿的潜力。
绿色黄金机遇:该公司拥有清洁水力发电的渠道,为其带来了独特的“绿色黄金”投资前景。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
首席财务官 Mark Ruus 介绍 Spanish Mountain Gold 2026 年 1 月 26 日在 VRIC 举办(时长:13 分钟)
https://www.youtube.com/watch?v=YzmLGz1Xhhg
Mark Ruus 在矿业领域拥有近三十年的从业经验。他最初在普华永道 (PwC) 工作,之后在金罗斯黄金公司 (Kinross Gold Corporation)、戈尔德科公司 (Goldcorp Inc.) 和普莱塞穹顶公司 (Placer Dome Inc.) 等领先的黄金矿业公司担任副总裁和高级副总裁税务职位。他丰富的经验和注册会计师 (CPA-CA) 资格,使其在国内外矿业公司的融资、成本控制、业务效率、合规、税务问题、并购和财务报告方面拥有广泛的知识。
===============================================================
西班牙山黄金 的战略转变:审计师更换和领导层过渡作为2026年增长的催化剂
===============================================================
- 西班牙山金矿更换审计师并任命新财务总监,以加强2027年建设决策的治理
- 新审计师BDO和Kim Leroux的专业知识旨在加强不列颠哥伦比亚省的财务监督和原住民参与。
- 运营准备包括更新的资源估算、2025年的钻探以及XRT技术,以优化黄金回收并减少碳足迹。
- 战略举措应对治理风险和可持续发展趋势,使公司能够应对监管和市场挑战。
采矿行业从勘探阶段过渡到开发阶段项目需要强有力的公司治理和运营准备。 对于西班牙山金业有限公司(Spanish Mountain Gold Ltd.)来说,这家初级勘探公司旨在发展成为新兴开发商,最近的战略举措——即更换审计师和领导层过渡——表明其有意努力将治理和技术能力与2027年的建设决策时间表对齐。 这些变化,加上运营方面的进展,使公司能够在资源受限且日益注重可持续发展的行业中,驾驭项目开发的复杂性。
审计师更换:加强发展阶段的治理严谨性
西班牙山金矿决定将Smythe LLP更换为BDO LLP作为其审计师,反映出其在财务监督和信誉方面的战略转变。 根据Business Wire的一份报告,审计委员会选择了BDO,因为其“在与矿业公司合作方面拥有丰富经验”,这是该公司在推进其西班牙山金矿项目至建设决策时的一个关键因素。 这一转变突显了公司认识到开发阶段项目需要具备行业专业知识的审计师,以应对监管审查和投资者期望。
这一过渡也突显了资本市场透明度的重要性。 通过在SEDAR+上提交更换审计师通知以及前任和继任审计师的必要函件,Spanish Mountain Gold展示了其遵守加拿大证券法规的合规性。 对于投资者来说,这一举措减少了与缺乏经验的审计师相关的治理风险,这是历史上困扰初级矿业公司的一个问题。 BDO在矿业审计方面的良好记录也可能促进与贷款人和合作伙伴的更顺畅互动,这些贷款人和合作伙伴在承诺大型项目之前通常要求进行严格的财务尽职调查。
领导层过渡:金·勒鲁的任命是治理的胜利
与审计师更换相辅相成的是金·勒鲁(Kim Leroux)被任命为财务总监,任命将于2026年1月2日生效。 Leroux在DeBeers和McEwen Mining Inc.的背景带来了深厚的矿业金融专业知识,这与公司的运营目标相一致。 值得注意的是,她在第一民族关系管理方面的经验为公司治理增添了一个关键维度,特别是在不列颠哥伦比亚省,在那里社区参与对项目许可和社会运营许可证至关重要。
从兼职合同首席财务官Mathew Lee过渡到Leroux的全职领导角色,也解决了初级矿业公司常见的一个弱点:财务管理不一致。 通过确保在2026年第一季度进行无缝交接,公司在最小化运营中断的同时,也为管理资本密集型的可行性研究和基础设施规划阶段做好了准备。 勒鲁对“开发和实施流程和系统”的关注表明了一种以治理为驱动的扩展运营的方法,这对于吸引机构投资至关重要。
运营准备:技术和可持续性驱动的进展
除了治理之外,Spanish Mountain Gold 的运营准备措施同样引人注目。 到2025年7月完成新的矿产资源估算(MRE)和初步经济评估(PEA)为后续的可行性研究提供了数据驱动的基础。 这些研究结合了2025年的勘探钻探计划,目标是10,000米,旨在通过在凤凰区和K区等关键目标地延伸矿化来降低项目风险。
加工技术的创新进一步增强了公司在开发阶段的准备。 根据《金融邮报》的报道,探索X射线透射(XRT)矿石分选技术——一种提高黄金回收率的技术——展示了优化项目经济性的积极方法。 同时,与BC Hydro的合作整合可再生柴油和电气化举措,突显了减少项目碳足迹的承诺,这已成为以ESG为重点的投资者日益关注的优先事项。 这些努力与全球矿业去碳化的趋势相一致,可能会在一个日益受到可持续性指标影响的监管和市场环境中,改善项目的长期可行性。
战略对齐与未来展望
西班牙山金矿公司在治理和运营准备方面的双重关注为其2027年的建设决策奠定了协同基础。 审计师更换和领导层过渡解决了内部能力限制,而技术进步和可持续发展举措则应对了外部挑战,如许可延误和资本成本通胀。 对于处于开发阶段的矿业公司来说,这些因素往往是项目成功与停滞之间的关键区别。
然而,风险仍然存在。 2025年的钻探计划结果将对验证矿产资源估算(MRE)的假设至关重要,而可行性研究的延迟可能会将建设决策推迟到2027年以后。 此外,Leroux将原住民合作伙伴关系整合到项目治理框架中的能力将决定监管审批的速度。 投资者必须密切关注这些里程碑,但公司的当前轨迹表明其成为生产商的道路结构良好。
结论
西班牙山金矿在2026年的战略转变——从审计和领导层变动到运营创新——展示了开发阶段的矿业公司如何减轻风险并提升价值。 通过优先考虑治理严格性和技术准备,公司正在为利用黄金行业的长期基本面做好准备,同时应对现代资本市场的ESG要求。 对于投资者来说,问题不再是项目能否推进,而是它能多快执行其雄心勃勃的时间表。
新闻参考
https://spanishmountaingold.com/news/2025/spa...scal-2025/
====================================
截至2025年7月3日的矿产资源量估算 (MRE)
====================================
https://investorshangout.com/images/MYImages/...timate.png
高品位K区矿床的资源量未包含在7月3日的初步经济评估 (PEA) 中。
=========================
K区非官方估算的黄金资源量
=========================
截至2月26日
https://investorshangout.com/images/MYImages/...K-zone.jpg
钻井区域:
https://investorshangout.com/images/MYImages/...argets.png
根据 K 区更新的化验结果,以及主矿区白银资源量与黄金资源量之比为 1.5,如果K区的吨位至少达到2亿吨,与主区相同,K 区在 2025 年 7 月 3 日的初步经济评估中将新增 5 million 盎司黄金和 7 million 盎司白银的探明 + 指示资源量。
2026 年新的初步经济评估报告 (PEA) 的新矿产资源估算报告 (MRE) 将显示已探明和已指示的黄金和白银资源量(已证实储量)分别为 9 million 盎司黄金和 13 million 盎司白银。如果此事成真,股价将会出现爆炸式增长。
2025年的钻探工作持续发现长段高品位金矿表明我们钻探的区域可能靠近金矿脉网络,而砂金的来源正是这些金矿脉。这些金矿脉在两亿年的风化作用下崩解,可见的金被腐蚀成细小的砂金。将高品位金矿纳入未来的初步经济评估将显著改善项目的经济效益。
“高品位”一词的含义取决于矿床类型。西班牙山项目主要是一个大型露天矿项目,其矿石品位通常低于窄脉地下矿。在此背景下,品位接近或超过1克/吨且矿体宽度较大的矿石被视为“高品位”,对项目开发具有重要的经济意义,尤其是在矿山运营初期。公司目前也在研究矿石分选技术,以期提高矿石品位,从而提升项目经济效益。
===================================
图表 - 黄金、白银、XAU、SPA.V、SPAUF
===================================
黄金价格 周线图 (价格仅在每日收盘时更新)
https://stockcharts.com/h-sc/ui?s=$GOLD&p...e_vignette
50 年黄金价格
https://mrci.com/pdf/gc.pdf
白银价格 周线图 (价格仅在每日收盘时更新日)
https://stockcharts.com/h-sc/ui?s=$SILVER&...e_vignette
50年白银价格 (价格单位:美分)
https://mrci.com/pdf/si.pdf
矿业指数 (XAU) 周线图
https://stockcharts.com/h-sc/ui?s=%24XAU&...9099899440
SPA.V 周线图
https://stockcharts.com/h-sc/ui?s=SPA.V&p...e_vignette
SPA.V - 新闻、交易数据
https://www.stockwatch.com/Quote/Detail.aspx?C:SPA.V
SPAUF.OTCQB 周线图
https://stockcharts.com/sc3/ui/?s=SPAUF&p...e_vignette
SPAUF 二级
https://www.otcmarkets.com/stock/SPAUF/overview
S3Y.FSE
https://ca.finance.yahoo.com/quote/S3Y.F/char...NlcyI6e319
=========
技术分析
=========
https://investorshangout.com/images/MYImages/...SPA.VM.jpg
https://investorshangout.com/images/MYImages/...alysis.png
https://investorshangout.com/images/MYImages/...alysis.png
SPA.V weekly
https://stockcharts.com/sc3/ui/?s=SPA.V&p...8609492691
看涨头肩形态案例
https://investorshangout.com/images/MYImages/...istory.png
=========
勘探潜力
=========
西班牙山黄金公司近期钻探工作持续发现长段金矿化,其中包括显著的高品位矿段,其品位通常高于项目整体平均品位。公司正重点勘探并确认这些高品位矿化区域,以期提升项目经济效益。
金品位及矿段详情
项目整体品位:2025年初步经济评估(PEA)中,已探明和已控制矿产资源的平均品位约为0.44克/吨。
高品位矿段:近期勘探钻探计划旨在确定可纳入未来矿山规划的高品位矿化带。这些勘探项目已取得多个显著的高品位矿段:
其中一个钻孔截获了123.00米、平均金品位为1.08克/吨的矿段,其中包括一段47.28米、平均金品位为2.29克/吨的高品位矿段。
另一个钻孔截获了一段107.50米、平均金品位为0.68克/吨的矿段,其中包括一段41.00米、平均金品位为0.98克/吨的矿段。
钻探还证实,在一段更宽的96.47米、平均金品位为0.91克/吨的矿段内,存在一段29.00米、平均金品位为2.55克/吨的连续高品位矿段。
在新的 Orca 断层区域进行的近地表钻探也显示出多处长截矿段,例如35.80米、金品位1.18克/吨和41.00米、金品位0.98克/吨。
“高品位”的定义
“高品位”一词与矿床类型相关。西班牙山项目主要是一个大型露天矿项目,其平均品位通常低于窄脉地下矿。在此背景下,品位接近或超过1克/吨且矿体宽度较大的矿段被认为是“高品位”,对项目的开发具有重要的经济意义,尤其是在矿山运营初期。公司还在研究矿石分选技术,以期提高矿石品位并改善项目经济效益。
=======================
认股权证、期权、内部股权
=======================
https://investorshangout.com/images/MYImages/...302026.jpg
内幕交易更新
https://www.barchart.com/stocks/quotes/SPA.VN/insider-trades
https://www.canadianinsider.com/company-insid...cker=SPA.V
========================
生产基础设施建设融资计划
========================
黄金价格
方案 1 - 与一家资金雄厚的矿业公司合资
方案 2A - 债务融资 (采用XRT选矿技术)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 2B - 债务融资 (无XRT选矿技术,处理所有岩石)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 3 - 收购交易
British Columbia Golden Triangle 地区的历史收购交易
Placer Dome 和 International Corona 以每股 $67 收购 Stikine Resources
https://www.northernminer.com/news/placer-sta...000178407/
Imperial Metals 以每股 $2.45 收购 American Bullion Minerals Ltd.
https://imperialmetals.com/for-our-shareholde...an-bullion
Newmont 以每股 $3.25 收购 GT Gold,交易金额达 $393 million
https://www.newmont.com/investors/news-releas...fault.aspx
澳大利亚黄金和铜生产商 Newcrest Mining 以 每股 $18.5 价格收购 Pretium Resources,交易金额达 $3.84 billion
https://magazine.cim.org/en/news/2021/newcres...e%20region
在 Ontario, Kinross 以 每股 $32 收购 Great Bear Resources, 交易金额达 $1.8 billion
https://www.globalminingreview.com/finance-bu...resources/
==============================
初步经济评估及 NI-43-101 技术报告
==============================
https://investorshangout.com/images/MYImages/...67_PEA.png
初步经济评估 (Preliminary Economic Assessment Economics)
https://spanishmountaingold.com/project/preli...economics/
August 18, 2025 - NI-43-101 技术报告 (Technical Report)
https://spanishmountaingold.com/site/assets/f...-final.pdf
===========================
25家金矿生产商的总体维持成本
===========================
https://www.mining.com/wp-content/uploads/202...31425A.gif
什么是总维持成本 (AISC)?
采矿业(尤其是黄金行业)的总维持成本 (AISC) 包括所有运营成本、维持性资本支出以及维持当前生产相关的其他成本。这包括现金成本、维持性资本支出、一般及行政管理 (G&A) 费用以及环境成本和矿场关闭成本。
总维持成本明细:
现金成本:
这些是采矿和加工的直接成本,包括劳动力、能源、消耗品和特许权使用费(扣除副产品抵扣)。
持续性资本支出:
这些是维持当前生产水平所需的投资,例如设备更换、矿山开发以及维持矿山当前产能所需的其他成本。
一般及行政管理 (G&A) 费用:
这些是与运营公司办公室和其他支持矿山运营的行政职能相关的成本。
环境及关闭成本:
这些包括与环境修复和矿山关闭相关的成本,例如复垦和退役。
勘探费用(维持性):
这些是维持当前生产水平和替换枯竭资源所需的勘探成本。
总维持成本 (AISC) 是一项综合指标,旨在更全面地反映开采一盎司黄金的总成本,而不仅仅是直接现金成本。
=====================
促成建造决策的关键步骤
=====================
西班牙山黄金 表示,生产基础建设会在 2026年做出决定,之后将开始进入为期两年的建设阶段。这一时间安排确保了正在进行的钻探计划、新的矿产资源估算(MRE)和新的初步经济评估(PEA)在2026年下半年完成,以及所有推进项目开发所需的报告和审批手续的顺利取得。新的PEA和MRE是优化项目建设的关键步骤。在做出建设决定之前,完成所有技术报告和监管审批是必要环节。
======
概述
======
矿业项目可以通过替代融资(例如流融资、矿权使用费融资或合资企业)在实现收入之前偿还贷款。这些融资方式的限制比传统债务更少,并且可以使用未来产量或收入作为抵押品,而不是现有收入。其他方法包括获得政府补助和奖励、通过包销协议预售部分未来产量,以及通过发行股票筹集股本。
==============
收入前融资方法
==============
流式协议:据 Stikeman Elliott 称,一家公司提供前期资本,以换取矿山未来矿产产量的一定比例,通常以折扣价出售。
特许权使用费融资:据 Stikeman Elliott 和 Lexology 称,融资方为项目提供资金,以换取项目未来收入或利润的一部分,这可以被视为对项目潜力的认可。
合资企业:与其他矿业公司或投资者合作可以分摊成本,分散财务负担,www.altfin.net 指出。
包销协议:将未来矿产产量的一部分预售给买家可以获得前期融资,并使贷款方对项目潜力充满信心。
政府资助:据 www.altfin.net 称,政府和开发银行有时会为符合经济或环境目标的项目提供赠款、贷款或税收优惠。
股权融资:通过发行股票筹集资金通常被认为是早期项目最简单的途径,因为它避免了债务融资的复杂性和严格要求。
这些方法的优势:
非稀释性(针对矿流/特许权使用费):Stikeman Elliott 指出,这些选择不会稀释公司原有股东权益。
灵活的条款:Appian Capital Advisory LLP 表示,矿流和特许权使用费结构比传统银行债务更灵活、限制更少,允许定制还款方案。
市场信心:矿流和特许权使用费等协议可被视为市场对项目的认可,从而可能增强投资者信心。
=========
盈利前景
=========
西班牙山地黄金公司 近期更新的初步经济评估 (PEA) 显示其经济前景良好,基准情景下净现值 (NPV) 为 10 亿加元,内部收益率 (IRR) 为 18.2%,随着金价上涨,净现值 (NPV) 和内部收益率 (IRR) 可能分别升至 23 亿加元和 32.0%。尽管该公司仍处于早期开发阶段,但该项目的传统露天开采、铣削作业、基础设施使用权以及具有施工和运营经验的新管理团队为其潜在的成功做出了贡献。
支持盈利能力的因素:
良好的经济效益:初步经济评估 (PEA) 预计,该项目将带来可观的财务回报,税后净现值 (NPV) 为 $1 billion,内部收益率 (IRR) 为 18.2%,基准金价为 2,450 美元/盎司;现货金价为 3,300 美元/盎司时,回报将更加可观。
强大的资源信心:经济分析基于高度的资源信心,涵盖了已探明和已指示的资源量,这些资源量是采矿项目成功的关键。
经验丰富的管理层:自 2022 年起,公司组建了新的董事会和管理团队,在项目管理、建设和运营方面拥有数十年的经验,为公司制定生产决策奠定了基础。
发达的基础设施:该项目将受益于不列颠哥伦比亚省中部完善的基础设施,包括公路交通便利以及毗邻威廉姆斯湖市的优势,从而降低运营复杂性和成本。
战略项目设计:该公司计划采用传统的露天开采和铣削作业,这是一种低风险的方法,比地下采矿更简单。
信息来源
https://spanishmountaingold.com/news/2025/spa...scal-2025/
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
https://investorshangout.com/images/MYImages/...uction.jpg
繁體中文
==============
最新消息發布
=============
2026年3月2日 - 西班牙山黃金 Phoenix 礦床顆粒礦石分選結果積極,凸顯產量提升潛力
https://www.stockwatch.com/News/Item/Z-C!SPA-3791171/C/SPA
基於 Phoenix 礦床樣品測試的X射線透射(XRT)結果顯示,透過大量剔除廢料和低品位礦石(約佔進料品質的50%至70%),礦石品位有望提升至樣品品位的兩倍甚至更高。顆粒礦石分選後,樣品中黃金的回收率達到85%至92%。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
2026年2月27日 - 西班牙山黃金 (TSX-V: SPA)(FSE: S3Y)(OTCQB: SPAUF)欣然宣布已與 Metso Canada Inc.(“Metso”)簽署了一份諒解備忘錄(“MoU”),該公司正朝著推進其西班牙山金礦(“SMG”)項目的可行性和許可邁進。 SMG項目位於加拿大不列顛哥倫比亞省的卡裡布區走廊。
https://www.stockwatch.com/News/Item/Z-C!SPA-3790618/C/SPA
==========================================
西班牙山黃金 正在逐步接近可行性和礦山建設決策
==========================================
Metso Canada 服務(視頻)
https://www.youtube.com/watch?v=wgiF9uZqDsE
https://www.metso.com/corporate/sustainabilit...-offering/
Metso Canada(前稱Metso Outotec) 是一家技術供應商,為提供多家公司採礦設備例如破碎機和磨機, 包括位於 British Columbia Cariboo 地區 的 Blackwater Mine。作為一家全球領先的工業公司,美卓在骨料、礦物加工和金屬精煉行業的可持續技術、端到端解決方案和服務方面處於領先地位。該公司致力於通過其產品提高客戶的能源和水資源利用效率,提升生產率並降低環境風險。破碎、篩分和研磨是其核心業務。
Metso業務的關鍵方面:
骨料:為採石和建筑行業提供破碎和篩分設備(移動和固定)。
礦物加工:提供採礦技術,包括磨礦機、分離、過濾和尾礦管理。
金屬精煉:提供金屬加工解決方案。
服務與磨損件:提供廣泛的售后服務、備件和磨損件,以優化設備性能。
可持續性:專注於“積極地球”解決方案,旨在減少客戶運營中的能源和水消耗。
================================================
西班牙山黃金-展望未來 ( 追隨 Blackwater Mine 的足跡 )
================================================
Blackwater Mine - Artmis Gold 擁有,位於西班牙山黃金 以西250公里,Prince George 以西南160公里。
https://www.google.ca/maps/place/Blackwater+M...FQAw%3D%3D
Artemis Gold 股價 (ARTG.V)
https://stockcharts.com/sc3/ui/?s=ARTG.V&...8838982129
礦山建設於2023年開始,並在22個月后完成,金銀冶煉將在2025年初開始。 作為加拿大最大的黃金開發項目之一,它是一個100%電氣化的設施,旨在成為一個低排放的露天礦。 它於2025年5月30日正式開業。
Metso(前身為Metso Outotec)交付了一台Superior MK-III 4265初級旋回破碎機、Nordberg HP900圓錐破碎機和一台14MW球磨機。
設備合同是通過Sedgman Canada Limited促成的,該公司負責工程、採購和施工的管理。
隨后的濕法廠(磨礦和CIL工藝)將運營從建設階段轉變為生產階段。
該地點設有一個完全電氣化的加工設施、一條225千伏的輸電線和一個重要的尾礦儲存設施。
該項目雇用了超過400人,其中有很高比例的本地和土著代表。
2025年12月,阿爾忒彌斯黃金公司批准了一項14.4億美元的二期擴建計劃,以增加產量。 建設計劃在2026年第三季度開始,預計在2028年第三季度完成。 擴建旨在提高加工能力,使其躋身加拿大最大的金礦之列。
設計時考慮了低碳足跡,用電動設備替代傳統燃料進行採礦和加工。
這是一個露天金銀礦,礦山壽命為22年,礦廠處理量為每天16,000噸,6年后可擴展至每天33,000噸,11年后可擴展至每天55,000噸。 它擁有800萬盎司的黃金、6220萬盎司的白銀的探明儲量,以及1170萬盎司的黃金、1.224億盎司的白銀的可能資源。
=======================
Blackwater Mine -資本支出
=======================
加拿大 British Columbia 的 Blackwater Mine 第一階段的初始資本支出(CAPEX)預計在 $730 million 加元 至 $750 million 加元之間。 截至2023年12月31日,約 $389 million 加元的初始資本已被支出,其中 84% 的指導范圍下限($615 million 加元)已合同承諾。
剩余資本支出: 截至2024年3月31日,第一階段剩余的資本支出估計在 $207 million 至 $227 million 加元之間。
范圍:第一階段集中於建設一個露天礦和一個年處理能力為 6 million 噸的加工設施。
后續第一階段升級(“第一階段A”)
2025年9月,Artemis Gold宣布計劃升級第一階段處理廠(稱為第一階段A),目標是在2026年第四季度之前將產能從每年 6 million 噸提高到 8 million 噸。
第一階段A資本成本:估計為 $100 million 至 $110 million 加元,由運營現金流資助。
目標:在利用建設第一階段的現有團隊的同時,提高產量和效率。
Artemis Gold 的 Blackwater Mine 第二階段(EP2)擴建預計將耗資 $1.44 billion 加元,旨在將處理能力擴展到每年 21 million 噸。 預計將在2028年左右完成,這一擴展將主要通過運營現金流來資助,目標是每年生產超過 500,000 盎司的黃金。
=================================
Blackwater Mine - 平均金品位和銀品位
=================================
前五年:平均金品位 1.29 克/噸。
后十七年:平均金品位 0.75 克/噸。
銀品位:預計礦山壽命期內平均銀品位為 5.78 克/噸。
儲量:探明和概略儲量總計估計為 334.3 million 噸,金品位 0.75 克/噸,含金量 8 million 盎司﹔銀品位 5.8 克/噸,含銀量 62 million 盎司。
前五年平均年產量:黃金 463,000 盎司,白銀 1.9 million 盎司
Blackwater Mine 建設視頻
1) 2025年2月 - 空中巡游
https://www.youtube.com/watch?v=ndcRuX42b3U
2) 2025年2月 - 礦業技術
https://www.youtube.com/watch?v=8WfAvX_Nzb4
3) 2025年2月 - 健康與安全
https://www.youtube.com/watch?v=ELbEBpNQMAw
4) 2025年2月 - 完工
https://www.youtube.com/watch?v=fpl3Vjd9slM
5) 2025年4月 - 首次黃金澆鑄於2025年1月進行
https://www.youtube.com/watch?v=E9nFlVjKIe4
6) 2025年5月30日 - 開幕式
https://www.youtube.com/watch?v=MOXjjZcGdYw
7) 2025年12月 - 第二階段:生產擴展
https://www.youtube.com/watch?v=R7xr4kidz4I
==========================================
西班牙山黃金 - 透過Gibraltar Mines的一生未來展望
==========================================
https://www.youtube.com/watch?v=yJmanh1uQMQ
Gibraltar Mines - 隸屬於 Tasedo Mines,位於西班牙山金礦以西50公裡處
https://www.google.ca/maps/place/Gibraltar+Mi...FQAw%3D%3D
Gibraltar Mines 是加拿大第二大露天銅鉬礦,其主要資源為低品位斑岩型銅鉬礦床,礦物成分包括黃銅礦、輝鉬礦、斑銅礦和赤銅礦。截至2024年12月31日,該礦擁有6.16億噸礦石,銅品位為0.26%,鉬品位為0.008%。
https://stockcharts.com/sc3/ui/?s=TKO.TO&...5512188236
=========
公司介绍
=========
https://spanishmountaingold.com/investors/presentations/
=====================
西班牙山黄金 - 運營更新
=====================
2024年和2025年的勘探鑽探計劃發現了提高礦產資源平均品位並可能增加礦坑內及附近資源量的機會。
公司目前的戰略重點仍然是優化、降低風險並推進其西班牙山金礦項目,力爭在 2027 年底前做出建設決策。
公司已與 ABH Engineering Inc. 合作啟動顆粒礦石分選項目,並與 OrePortal Technologies Ltd. 合作開展散裝礦石分選研究。
如果 XRT 礦石分選項目成功實施,資本支出將減少,而未來的黃金產量將提高。
2025年8月27日,該公司完成了 $7,199,968 股權融資。 ( https://spanishmountaingold.com/news/2025/spa...placement/ ). 這筆資金足以支持秋季鑽探計劃、可行性研究和礦石分選計劃,直至2026年。執行長彼得馬赫表示,未來的融資將採用非稀釋性方式。
認股權證融資:行使面額分別為 $0.25 和 $0.18 的未行使認股權證(分別於 2026 5月31日 和 11月15日 到期)將在 2026 年為國庫帶來 $10.9 million,有助於資助該計畫的進展。
摘自2024年5月31日的融資協議:"每股面額 $0.25 的認股權證將於2026年5月30日到期。每份認股權證賦予持有人自發行日起24個月內以每股 $0.25 的價格購買一股額外股份(“認股權證股份”)的權利,但如果 普通股的10日成交量加權平均價格超過每股 $0.30, 則認股權證提前到期"
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...3-million/
公司已聘請領先的企業贊助研究公司 Atrium Research Corporation 提供服務。Atrium 將為公司提供一系列研究服務,並向潛在投資者介紹公司的投資價值。Atrium 還將安排公司管理團隊接受視頻採訪,以訪談形式闡述投資價值。
Atrium Research 將 SPA.V 的目標價上調至 $0.80
https://www.atriumresearch.ca/spa
目前的勘探鑽探化驗結果持續顯示,在新劃定的 Orca 斷層靶區內,沿走向長度超過300公尺處存在顯著的高品位礦化,且該礦化帶已在兩個平行相鄰的鑽孔剖面上連續延伸。鑽孔 25-DH-1299 的深部交匯處,金品位為 1.67 克/噸,厚度為 45.54 米,位於 2025 年礦產資源估算 (MRE) 的約束露天礦坑邊界之下,證實了歷史鑽探結果,即深處存在更高品位的礦產化,並強調需要進行更深層的探礦潛力。
2025年7月3日完成的初步經濟評估和NI-43-101技術報告將為2026年開展新的初步經濟評估和礦產資源評估奠定基礎。屆時,將在高品位K區和鳳凰區探明更多金礦資源后,啟動露天礦坑作業。公司將啟動新的預可行性研究(PFS),或可能直接進入可行性研究(FS)。
==========
未來展望
==========
西班牙山黃金 的市值遠低於同業。分析師給出的目標價表明該公司被低估,具有巨大的成長潛力, 原因包括即將發布的資源更新報告、潛在的高品位礦藏發現,以及利用現有水力發電資源開發獨特的「綠色黃金」機會。
即將到來的催化劑:新的初步經濟評估和資源估算預計將重新評估該股的價格。
礦化潛力:該項目擁有覆蓋廣泛、品位高的礦化帶,表明未來存在發現金礦的潛力。
綠色黃金機遇:該公司擁有清潔水力發電的渠道,為其帶來了獨特的“綠色黃金”投資前景。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
財務長 Mark Ruus 介紹 Spanish Mountain Gold 2026 年 1 月 26 日在 VRIC 舉行(長度:13 分鐘)
https://www.youtube.com/watch?v=YzmLGz1Xhhg
Mark Ruus 在礦業領域擁有近三十年的經驗。他最初在普華永道 (PwC) 工作,之後在金羅斯黃金公司 (Kinross Gold Corporation)、戈爾德科公司 (Goldcorp Inc.) 和普萊塞穹頂公司 (Placer Dome Inc.) 等領先的黃金礦業公司擔任副總裁和高級副總裁稅務職位。他豐富的經驗和註冊會計師 (CPA-CA) 資格,使其在國內外礦業公司的融資、成本控制、業務效率、合規、稅務問題、併購和財務報告方面擁有廣泛的知識。
================================================================
西班牙山黃金 的戰略轉變:審計師更換和領導層過渡作為2026年增長的催化劑
================================================================
- 西班牙山黃金 更換審計師並任命新財務總監,以加強2027年建設決策的治理
- 新審計師BDO和Kim Leroux的專業知識旨在加強不列顛哥倫比亞省的財務監督和原住民參與。
- 運營准備包括更新的資源估算、2025年的鑽探以及XRT技術,以優化黃金回收並減少碳足跡。
- 戰略舉措應對治理風險和可持續發展趨勢,使公司能夠應對監管和市場挑戰。
採礦行業從勘探階段過渡到開發階段項目需要強有力的公司治理和運營准備。 對於西班牙山金業有限公司(Spanish Mountain Gold Ltd.)來說,這家初級勘探公司旨在發展成為新興開發商,最近的戰略舉措——即更換審計師和領導層過渡——表明其有意努力將治理和技術能力與2027年的建設決策時間表對齊。 這些變化,加上運營方面的進展,使公司能夠在資源受限且日益注重可持續發展的行業中,駕馭項目開發的復雜性。
審計師更換:加強發展階段的治理嚴謹性
西班牙山金礦決定將Smythe LLP更換為BDO LLP作為其審計師,反映出其在財務監督和信譽方面的戰略轉變。 根據Business Wire的一份報告,審計委員會選擇了BDO,因為其“在與礦業公司合作方面擁有豐富經驗”,這是該公司在推進其西班牙山金礦項目至建設決策時的一個關鍵因素。 這一轉變突顯了公司認識到開發階段項目需要具備行業專業知識的審計師,以應對監管審查和投資者期望。
這一過渡也突顯了資本市場透明度的重要性。 通過在SEDAR+上提交更換審計師通知以及前任和繼任審計師的必要函件,Spanish Mountain Gold展示了其遵守加拿大証券法規的合規性。 對於投資者來說,這一舉措減少了與缺乏經驗的審計師相關的治理風險,這是歷史上困擾初級礦業公司的一個問題。 BDO在礦業審計方面的良好記錄也可能促進與貸款人和合作伙伴的更順暢互動,這些貸款人和合作伙伴在承諾大型項目之前通常要求進行嚴格的財務盡職調查。
領導層過渡:金·勒魯的任命是治理的勝利
與審計師更換相輔相成的是金·勒魯(Kim Leroux)被任命為財務總監,任命將於2026年1月2日生效。 Leroux在DeBeers和McEwen Mining Inc.的背景帶來了深厚的礦業金融專業知識,這與公司的運營目標相一致。 值得注意的是,她在第一民族關系管理方面的經驗為公司治理增添了一個關鍵維度,特別是在不列顛哥倫比亞省,在那裡社區參與對項目許可和社會運營許可証至關重要。
從兼職合同首席財務官Mathew Lee過渡到Leroux的全職領導角色,也解決了初級礦業公司常見的一個弱點:財務管理不一致。 通過確保在2026年第一季度進行無縫交接,公司在最小化運營中斷的同時,也為管理資本密集型的可行性研究和基礎設施規劃階段做好了准備。 勒魯對“開發和實施流程和系統”的關注表明了一種以治理為驅動的擴展運營的方法,這對於吸引機構投資至關重要。
運營准備:技術和可持續性驅動的進展
除了治理之外,Spanish Mountain Gold 的運營准備措施同樣引人注目。 到2025年7月完成新的礦產資源估算(MRE)和初步經濟評估(PEA)為后續的可行性研究提供了數據驅動的基礎。 這些研究結合了2025年的勘探鑽探計劃,目標是10,000米,旨在通過在鳳凰區和K區等關鍵目標地延伸礦化來降低項目風險。
加工技術的創新進一步增強了公司在開發階段的准備。 根據《金融郵報》的報道,探索X射線透射(XRT)礦石分選技術——一種提高黃金回收率的技術——展示了優化項目經濟性的積極方法。 同時,與BC Hydro的合作整合可再生柴油和電氣化舉措,突顯了減少項目碳足跡的承諾,這已成為以ESG為重點的投資者日益關注的優先事項。 這些努力與全球礦業去碳化的趨勢相一致,可能會在一個日益受到可持續性指標影響的監管和市場環境中,改善項目的長期可行性。
戰略對齊與未來展望
西班牙山金礦公司在治理和運營准備方面的雙重關注為其2027年的建設決策奠定了協同基礎。 審計師更換和領導層過渡解決了內部能力限制,而技術進步和可持續發展舉措則應對了外部挑戰,如許可延誤和資本成本通脹。 對於處於開發階段的礦業公司來說,這些因素往往是項目成功與停滯之間的關鍵區別。
然而,風險仍然存在。 2025年的鑽探計劃結果將對驗証礦產資源估算(MRE)的假設至關重要,而可行性研究的延遲可能會將建設決策推遲到2027年以后。 此外,Leroux將原住民合作伙伴關系整合到項目治理框架中的能力將決定監管審批的速度。 投資者必須密切關注這些裡程碑,但公司的當前軌跡表明其成為生產商的道路結構良好。
結論
西班牙山金礦在2026年的戰略轉變——從審計和領導層變動到運營創新——展示了開發階段的礦業公司如何減輕風險並提升價值。 通過優先考慮治理嚴格性和技術准備,公司正在為利用黃金行業的長期基本面做好准備,同時應對現代資本市場的ESG要求。 對於投資者來說,問題不再是項目能否推進,而是它能多快執行其雄心勃勃的時間表
新聞參考
https://spanishmountaingold.com/news/2025/spa...scal-2025/
====================================
截至2025年7月3日的礦產資源量估算 (MRE)
====================================
https://investorshangout.com/images/MYImages/...timate.png
高品位K區礦床的資源量未包含在7月3日的初步經濟評估 (PEA) 中。
=============================
K區非官方估算的黄金资源量估算
=============================
截至2月26日
https://investorshangout.com/images/MYImages/...K-zone.jpg
鑽井區域:
https://investorshangout.com/images/MYImages/...argets.png
根據 K 區更新的化驗結果,以及主礦區白銀資源量與黃金資源量之比為 1.5,若K區的噸位至少達到2億噸,與主區相同,K 區在 2025 年 7 月 3 日的初步經濟評估中將新增 5 million 盎司黃金和 7 million 盎司白銀的探明 + 指示資源量。
2026 年新的初步經濟評估報告 (PEA) 的新礦產資源估算報告 (MRE) 將顯示已探明和已指示的黃金和白銀資源量(已證實儲量)分別為 9 million 盎司黃金和 13 million 盎司白銀。如果此事成真,股價將會出現爆炸性成長。
2025年的鑽探工作持續發現長段高品位金礦表明我們鑽探的區域可能靠近金礦脈網絡,而砂金的來源正是這些金礦脈。這些金礦脈在兩億年的風化作用下崩解,可見的金被腐蝕成細小的砂金。將高品位金礦納入未來的初步經濟評估將顯著改善項目的經濟效益。
“高品位”一詞的含義取決於礦床類型。西班牙山項目主要是一個大型露天礦項目,其礦石品位通常低於窄脈地下礦。在此背景下,品位接近或超過1克/噸且礦體寬度較大的礦石被視為“高品位”,對項目開發具有重要的經濟意義,尤其是在礦山運營初期。公司目前也在研究礦石分選技術,以期提高礦石品位,從而提升項目經濟效益。
====================================
圖表 - 黃金、白銀、XAU、SPA.V、SPAUF
====================================
黃金價格 周線圖 (價格僅在每日收盤時更新)
https://stockcharts.com/h-sc/ui?s=$GOLD&p...e_vignette
50 年黃金價格
https://mrci.com/pdf/gc.pdf
白銀價格 周線圖 (價格僅在每日收盤時更新日)
https://stockcharts.com/h-sc/ui?s=$SILVER&...e_vignette
50年白銀價格 (價格單位:美分)
https://mrci.com/pdf/si.pdf
礦業指數 (XAU) 周線圖
https://stockcharts.com/h-sc/ui?s=%24XAU&...9099899440
SPA.V 周線圖
https://stockcharts.com/h-sc/ui?s=SPA.V&p...e_vignette
SPA.V - 新聞、交易數據
https://www.stockwatch.com/Quote/Detail.aspx?C:SPA.V
SPAUF.OTCQB 周線圖
https://stockcharts.com/sc3/ui/?s=SPAUF&p...e_vignette
SPAUF.OTCQB 二級
https://www.otcmarkets.com/stock/SPAUF/overview
S3Y.FSE
https://ca.finance.yahoo.com/quote/S3Y.F/char...NlcyI6e319
=========
技術分析
=========
https://investorshangout.com/images/MYImages/...SPA.VM.jpg
https://investorshangout.com/images/MYImages/...alysis.png
https://investorshangout.com/images/MYImages/...alysis.png
SPA.V weekly
https://stockcharts.com/sc3/ui/?s=SPA.V&p...8609492691
看漲頭肩形態案例
https://investorshangout.com/images/MYImages/...istory.png
=========
勘探潛力
=========
西班牙山黃金 近期鑽探工作持續發現長段金礦化,其中包括顯著的高品位礦段,其品位通常高於項目整體平均品位。公司正重點勘探並確認這些高品位礦化區域,以期提升項目經濟效益。
金品位及礦段詳情
項目整體品位:2025年初步經濟評估(PEA)中,已探明和已控制礦產資源的平均品位約為0.44克/噸。
高品位礦段:近期勘探鑽探計劃旨在確定可納入未來礦山規劃的高品位礦化帶。這些勘探項目已取得多個顯著的高品位礦段:
其中一個鑽孔截獲了123.00米、平均金品位為1.08克/噸的礦段,其中包括一段47.28米、平均金品位為2.29克/噸的高品位礦段。
另一個鑽孔截獲了一段107.50米、平均金品位為0.68克/噸的礦段,其中包括一段41.00米、平均金品位為0.98克/噸的礦段。
鑽探還証實,在一段更寬的96.47米、平均金品位為0.91克/噸的礦段內,存在一段29.00米、平均金品位為2.55克/噸的連續高品位礦段。
在新的 Orca 斷層區域進行的近地表鑽探也顯示出多處長截礦段,例如35.80米、金品位1.18克/噸和41.00米、金品位0.98克/噸。
“高品位”的定義
“高品位”一詞與礦床類型相關。西班牙山項目主要是一個大型露天礦項目,其平均品位通常低於窄脈地下礦。在此背景下,品位接近或超過1克/噸且礦體寬度較大的礦段被認為是“高品位”,對項目的開發具有重要的經濟意義,尤其是在礦山運營初期。公司還在研究礦石分選技術,以期提高礦石品位並改善項目經濟效益。
=======================
認股權証、期權、內部股權
=======================
https://investorshangout.com/images/MYImages/...302026.jpg
內幕交易更新
https://www.barchart.com/stocks/quotes/SPA.VN/insider-trades
https://www.canadianinsider.com/company-insid...cker=SPA.V
========================
生產基礎設施建設融資計劃
========================
黃金價格
方案 1 - 與一家資金雄厚的礦業公司合資
方案 2A - 債務融資 (採用XRT選礦技術)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 2B - (無XRT選礦技術,處理所有岩石)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 3 - 收購交易
British Columbia Golden Triangle 地區的歷史收購交易
Placer Dome 和 International Corona 以每股 $67 收購 Stikine Resources
https://www.northernminer.com/news/placer-sta...000178407/
Imperial Metals 以每股 $2.45 收購 American Bullion Minerals Ltd.
https://imperialmetals.com/for-our-shareholde...an-bullion
Newmont 以每股 $3.25 收購 GT Gold,交易金額達 $393 million
https://www.newmont.com/investors/news-releas...fault.aspx
澳大利亞黃金和銅生產商 Newcrest Mining 以 每股 $18.5 收購 Pretium Resources, 交易金額達 $3.84 billion
https://magazine.cim.org/en/news/2021/newcres...e%20region
在 Ontario, Kinross 以 每股 $32 收購 Great Bear Resources, 交易金額達 $1.8 billion
https://www.globalminingreview.com/finance-bu...resources/
=============================
初步經濟評估及 NI-43-101 技術報告
=============================
https://investorshangout.com/images/MYImages/...67_PEA.png
初步经济评估 (Preliminary Economic Assessment Economics)
https://spanishmountaingold.com/project/preli...economics/
August 18, 2025 - NI-43-101 技術報告 (Technical Report)
https://spanishmountaingold.com/site/assets/f...-final.pdf
===========================
25家金礦生產商的總體維持成本
===========================
https://www.mining.com/wp-content/uploads/202...31425A.gif
什麼是總維持成本 (AISC)?
採礦業(尤其是黃金行業)的總維持成本 (AISC) 包括所有運營成本、維持性資本支出以及維持當前生產相關的其他成本。這包括現金成本、維持性資本支出、一般及行政管理 (G&A) 費用以及環境成本和礦場關閉成本。
總維持成本明細:
現金成本:
這些是採礦和加工的直接成本,包括勞動力、能源、消耗品和特許權使用費(扣除副產品抵扣)。
持續性資本支出:
這些是維持當前生產水平所需的投資,例如設備更換、礦山開發以及維持礦山當前產能所需的其他成本。
一般及行政管理 (G&A) 費用:
這些是與運營公司辦公室和其他支持礦山運營的行政職能相關的成本。
環境及關閉成本:
這些包括與環境修復和礦山關閉相關的成本,例如復墾和退役。
勘探費用(維持性):
這些是維持當前生產水平和替換枯竭資源所需的勘探成本。
總維持成本 (AISC) 是一項綜合指標,旨在更全面地反映開採一盎司黃金的總成本,而不僅僅是直接現金成本。
======================
促成建造決策的關鍵步驟
======================
西班牙山黃金 表示,生產基礎建設會在 2026年做出決定,之后將開始進入為期兩年的建設階段。這一時間安排確保了正在進行的鑽探計劃、新的礦產資源估算(MRE)和新的初步經濟評估(PEA)在2026年下半年完成,以及所有推進項目開發所需的報告和審批手續的順利取得。新的PEA和MRE是優化項目建設的關鍵步驟。在做出建設決定之前,完成所有技術報告和監管審批是必要環節。
======
概述
======
礦業項目可以通過替代融資(例如流融資、礦權使用費融資或合資企業)在實現收入之前償還貸款。這些融資方式的限制比傳統債務更少,並且可以使用未來產量或收入作為抵押品,而不是現有收入。其他方法包括獲得政府補助和獎勵、通過包銷協議預售部分未來產量,以及通過發行股票籌集股本。
===============
收入前融資方法
===============
流式協議:據 Stikeman Elliott 稱,一家公司提供前期資本,以換取礦山未來礦產產量的一定比例,通常以折扣價出售。
特許權使用費融資:據 Stikeman Elliott 和 Lexology 稱,融資方為項目提供資金,以換取項目未來收入或利潤的一部分,這可以被視為對項目潛力的認可。
合資企業:與其他礦業公司或投資者合作可以分攤成本,分散財務負擔,www.altfin.net 指出。
包銷協議:將未來礦產產量的一部分預售給買家可以獲得前期融資,並使貸款方對項目潛力充滿信心。
政府資助:據 www.altfin.net 稱,政府和開發銀行有時會為符合經濟或環境目標的項目提供贈款、貸款或稅收優惠。
股權融資:通過發行股票籌集資金通常被認為是早期項目最簡單的途徑,因為它避免了債務融資的復雜性和嚴格要求。
這些方法的優勢:
非稀釋性(針對礦流/特許權使用費):Stikeman Elliott 指出,這些選擇不會稀釋公司原有股東權益。
靈活的條款:Appian Capital Advisory LLP 表示,礦流和特許權使用費結構比傳統銀行債務更靈活、限制更少,允許定制還款方案。
市場信心:礦流和特許權使用費等協議可被視為市場對項目的認可,從而可能增強投資者信心。
=========
盈利前景
=========
西班牙山黃金 近期更新的初步經濟評估 (PEA) 顯示其經濟前景良好,基准情景下淨現值 (NPV) 為 $1 billion,內部收益率 (IRR) 為 18.2%,隨著金價上漲,淨現值 (NPV) 和內部收益率 (IRR) 可能分別升至 23 億加元和 32.0%。盡管該公司仍處於早期開發階段,但該項目的傳統露天開採、銑削作業、基礎設施使用權以及具有施工和運營經驗的新管理團隊為其潛在的成功做出了貢獻。
支持盈利能力的因素:
良好的經濟效益:初步經濟評估 (PEA) 預計,該項目將帶來可觀的財務回報,稅后淨現值 (NPV) 為 $1 billion, 內部收益率 (IRR) 為 18.2%,基准金價為 2,450 美元/盎司﹔現貨金價為 3,300 美元/盎司時,回報將更加可觀。
強大的資源信心:經濟分析基於高度的資源信心,涵蓋了已探明和已指示的資源量,這些資源量是採礦項目成功的關鍵。
經驗豐富的管理層:自 2022 年起,公司組建了新的董事會和管理團隊,在項目管理、建設和運營方面擁有數十年的經驗,為公司制定生產決策奠定了基礎。
發達的基礎設施:該項目將受益於不列顛哥倫比亞省中部完善的基礎設施,包括公路交通便利以及毗鄰威廉姆斯湖市的優勢,從而降低運營復雜性和成本。
戰略項目設計:該公司計劃採用傳統的露天開採和銑削作業,這是一種低風險的方法,比地下採礦更簡單。
西班牙山黄金 - 运营更新
西班牙山黄金 - 運營更新
https://investorshangout.com/images/MYImages/...uction.jpg
Peter Mah of Spanish Mountain Gold Ltd. presents at Metals Investor Forum in Toronto | February 2026 (10 minutes)
https://www.youtube.com/watch?v=I2XVcbte6tU
Jason Dunning & Peter Mah of Spanish Mountain Gold talks to John Kaiser at the Metals Investor Forum 2026 (20 minutes)
https://www.youtube.com/watch?v=BgDAvF5cv9w
John Kaiser: "I like to finish off by saying that in my 40-year of career I have never seen a situation like today where the market is underpricing ounce in the ground gold project relative where gold price is. That my entire history has been, oh yeah, we are pricing for the future price of gold. Now we have the opposite and there's going be an inflection coming sometimes this year where people realize oh, the market has it wrong. So I am looking forward ......."
Peter Mah: 4 million ounces (gold), 5 million ounces (silver), 100 million market cap, hugely undervalued, great opportunity, can't agree anymore.
Biography of Jason Dunning
https://people.equilar.com/bio/person/jason-d...n/50679277
https://www.linkedin.com/in/jasondunning/
Biography of John Kaiser
https://cambridgehouse.com/u/2155/john-kaiser
===================
Latest News Release
===================
March 2, 2026 - Spanish Mountain Gold Receives Positive Particle Ore Sorting Results for the Phoenix Deposit Highlighting Production Upside
https://www.stockwatch.com/News/Item/Z-C!SPA-3791171/C/SPA
X-ray transmission (“XRT”) results based on the samples tested from the Phoenix deposit show an upgrade potential of two or more times the grade of the sample through a high mass rejection of waste and lower-grade material in the order of 50% to 70% of the feed mass. Particle ore sorting resulted 85% to 92% recovery of gold from the samples.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
February 27, 2026 - Spanish Mountain Gold Ltd. (the "Company" or "Spanish Mountain Gold"
(TSX-V: SPA) (FSE: S3Y) (OTCQB: SPAUF) is pleased to announce that it has signed a Memorandum of Understanding (“MoU”) with Metso Canada Inc. (“Metso”), as it moves closer to advancing its Spanish Mountain Gold (“SMG”) project towards feasibility and permitting. The SMG project is located in the Cariboo District corridor in British Columbia, Canada. https://www.stockwatch.com/News/Item/Z-C!SPA-3790618/C/SPA
=================================================================
Spanish Mountain Gold is inching towards Feasibility and Mine Building Decision
=================================================================
Metso Canada services (video)
https://www.youtube.com/watch?v=wgiF9uZqDsE
Metso website
https://www.metso.com/corporate/sustainabilit...-offering/
Metso Canada (formerly Metso Outotec) is a technology provider that supplies mining equipment such as crushers and grinding mills to various companies, including recent project like Blackwater Mine in the Cariboo region of British Columbia. It is a leading global industrial company and a frontrunner in sustainable technologies, end-to-end solutions and services for the aggregates, minerals processing and metals refining industries. They focus on improving their customers’ energy and water efficiency, increase their productivity and reduce environmental risks with their product. Crushing, screening and grinding is their core business.
Key Aspects of Metso’s Business:
Aggregates: Provides crushing and screening equipment (mobile and fixed) for quarrying and construction industries.
Minerals Processing: Offers technology for mining, including grinding mills, separation, filtration, and tailings management.
Metals Refining: Provides solutions for metal processing.
Services & Wears: Delivers a broad portfolio of aftermarket services, spare parts, and wear parts to optimize equipment performance.
Sustainability: Focuses on "Planet Positive" solutions aimed at reducing energy and water consumption in customer operations.
==========================================================================
Spanish Mountain Gold - Vision For The Future ( following the footsteps of Blackwater Mine )
==========================================================================
Blackwater Mine - Owned by Artemis Gold, located 250 kilometers northwest of Spanish Mountain Gold and 160 km southwest of Prince George
https://www.google.ca/maps/place/Blackwater+M...FQAw%3D%3D
Artemis Gold share price ( ARTG.V )
https://stockcharts.com/sc3/ui/?s=ARTG.V&...8838982129
Mine construction began in 2023 and completed after 22-month with gold/silver pouring starting in early 2025. As one of Canada's largest gold development projects, it is a 100% electrified facility designed to be a low-emission, open-pit mine. It officially opened on May 30, 2025.
Metso Canada (formerly Metso Outotec) delivered a Superior MK-III 4265 primary gyratory 18MW SAG mill crusher, a Nordberg HP900 cone crushers, and a 14MW ball mill to Blackwater Mine.
The equipment contract was facilitated through Sedgman Canada Limited, which is managing the engineering, procurement, and construction.
Subsequent wet plant (milling and CIL circuit) transitioned the operation from construction to production.
The site features a fully electrified processing facility, a 225kV transmission line, and a significant tailings storage facility.
The project employs over 400 people, with a high percentage of local and Indigenous representation.
In December 2025 Artemis Gold approved a $1.44 billion Phase 2 expansion to increase production. Construction is planned for Q3 2026 and completion is expected in Q3 2028. The expansion aims to boost processing capacity, positioning it among Canada's largest gold mines.
Designed with a low carbon footprint, replacing traditional fuels with electric equipment for mining and processing.
It is an open pit gold and silver mine with mine life of 22 year and with mill throughput of 16,000 tpd, expandable to 33,000 tpd in year 6 and 55,000 tpd in year 11. It has Proven Reserves of 8 million ounces of gold, 62.2 million ounces of silver and Probable Resources of 11.7 million ounce of gold, 122.4 million ounces of silver.
=================================
Blackwater Mine - Capital Expenditure
================================
The initial capital expenditure (CAPEX) for Phase 1 of the Blackwater Mine in British Columbia, Canada, was guided to be between C$730 million and C$750 million. As of December 31, 2023, approximately C$389 million of this initial capital had been spent, with 84% of the lower end of the guided range (C$615 million) contractually committed.
Remaining Capex: As of March 31, 2024, remaining Phase 1 capital expenditures were estimated at C$207 to C$227 million.
Scope: Phase 1 focused on building an open-pit mine and a processing facility with a capacity of 6 million tonnes per annum (Mtpa).
Subsequent Phase 1 Upgrades ("Phase 1A"
In September 2025, Artemis Gold announced plans to upgrade the Phase 1 processing plant (dubbed Phase 1A), aiming to increase capacity from 6 Mtpa to 8 Mtpa by Q4 2026.
Phase 1A Capital Cost: Estimated at C$100–C$110 million, to be funded by operating cash flows.
Goal: To increase throughput and efficiency while leveraging the existing team that built Phase 1.
Artemis Gold's Phase 2 (EP2) expansion of the Blackwater mine in B.C. is estimated to cost $1.44 billion CAD, designed to expand processing capacity to 21 Mtpa. Expected to be completed around 2028, this expansion will be funded primarily through operating cash flows, aiming to produce over 500,000 ounces of gold annually.
==============================================
Blackwater Mine - Average gold grade and silver grade
==============================================
First 5 Years: Averaging 1.29 g/t gold.
Subsequent 17 years: Average 0.75 g/t gold.
Silver Grade: The average silver grade is estimated to be 5.78 g/t Ag over the life of the mine.
Reserve Basis: Total proven and probable reserves are estimated at 334.3 million tonnes at 0.75 g/t gold with gold content of 8 million ounces and 5.8 g/t silver with silver content of 62 million ounces.
First 5 years average annual production: 463,000 ounces of gold and 1.9 million ounces of silver.
==============================
Blackwater Mine construction videos
=============================
1) Feb 2025 - Aerial tour
https://www.youtube.com/watch?v=ndcRuX42b3U
2) Feb 2025 - Mining Technology
https://www.youtube.com/watch?v=8WfAvX_Nzb4
3) Feb 2025 - Health and Safety
https://www.youtube.com/watch?v=ELbEBpNQMAw
4) Feb 2025 - Completion of construction
https://www.youtube.com/watch?v=fpl3Vjd9slM
5) April 2025 - First gold pouring occurred in January 2025
https://www.youtube.com/watch?v=E9nFlVjKIe4
6 May 30, 2025 - Opening ceremony
https://www.youtube.com/watch?v=MOXjjZcGdYw
7) Dec 2025 - Phase 2: Production Expansion
https://www.youtube.com/watch?v=R7xr4kidz4I
==============================================================
Spanish Mountain Gold - Vision for the future through the life of Gibraltar Mines
==============================================================
https://www.youtube.com/watch?v=yJmanh1uQMQ
Gibraltar Mines - Owned by Taseko Mines, located 50 kilometers west of Spanish Mountain Gold
https://www.google.ca/maps/place/Gibraltar+Mi...FQAw%3D%3D
The Gibraltar Mine is the second-largest open-pit copper-molybdenum mine in Canada, owned and operated by Taseko Mines. Its primary resource is low-grade porphyry copper-molybdenum deposit containing minerals chalcopyrite, molybdenite, bornite, and cuprite. As of December 31, 2024, the mine has 616 million tons of 0.26% copper and 0.008% molybdenum.
https://stockcharts.com/sc3/ui/?s=TKO.TO&...5512188236
===================
Corporate Presentation
===================
https://spanishmountaingold.com/investors/presentations/
===============
Operation Update
===============
The 2024 and 2025 exploration drill program identified opportunities to improve the average grade of the mineral resources and potentially grow the in-pit and near pit resources.
The Company’s current strategy remains focused on optimizing, de-risking and advancing its Spanish Mountain Gold Project towards a build decision in 2026.
The company has commenced a particle ore sorting program with ABH Engineering Inc. and a bulk ore sorting study with OrePortal Technologies Ltd.
If the XRT ore sorting program will be successfully implemented, capital expenditure will be reduced while future gold productivity will increase.
On August 27, 2025 the company closed the $7,199,968 equity financing. ( https://spanishmountaingold.com/news/2025/spa...placement/ ). The fund will be sufficient to fund the Fall drill program, feasibility study and ore sorting program till 2026. According to CEO Peter Mah, future financing will employ non-dilutive approach.
Warrant Financing: The exercise of 25 cents and 18 cents outstanding warrants expiring on May 30 and November 15 of 2026 respectively will bring C$10.9 million into the treasury in 2026, helping to fund the project's progression.
Excerpt from the May 31,2024 financing: "The 25 cent warrants will expire on May 30, 2026. Each Warrant entitles the holder thereof to purchase one additional Share (a “Warrant Share”) at a price of $0.25 per Warrant Share for a period of 24 months from the date of issuance, subject to earlier expiry if the 10-day volume weighted average price of the Common Shares on the TSX Venture Exchange (the “TSXV”) exceeds $0.30 per Common Share".
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...3-million/
The company has engaged the services of Atrium Research Corporation, a leading company sponsored research firm. Atrium will produce a range of research services to the Company and present the Company’s investment case to potential investors. Atrium will also host video interviews with the Company’s management team to present the investment case in an interview format.
Atrium Research increased SPA.V price target to $0.80
https://www.atriumresearch.ca/spa
Current exploration drilling assay results continues to intersect significant higher-grade mineralization over 300 m in strike length in the newly defined Orca Fault target and the continuity can now be traced across two parallel, adjacent drill sections. The deep intersection in drill hole 25-DH-1299, grading 1.67 g/t gold over 45.54 m confirms historical drilling that there is higher-grade mineralization at depth and additional drilling is required to quantify the deeper mineral potential.
The completion of the Preliminary Economic Assessment and NI-43-101 Technical Report on July 3, 2025 will form the basis for a new PEA and new MRE in 2026 after additional gold resources is delineated into the in pit operation from the high grade K-zone and Phoenix zone. The Company will begin a new Pre-Feasibility Study (PFS) or potentially advancing directly to a Feasibility Study (“FS”).
=============
Future Prospect
=============
Spanish Mountain Gold's market capitalization is well below its peer. With analysts providing price targets suggesting it is undervalued, potentially offering significant growth. The company's undervaluation stems from factors like a pending resource update, potential high-grade discoveries, and a unique "green gold" opportunity from available hydroelectric power.
Upcoming Catalyst: A new preliminary economic assessment and new resource estimate are expected to re-evaluate the stock's price.
Mineralization Potential: The project has high-grade mineralization across a significant length, suggesting the potential for future discoveries.
Green Gold Opportunity: The company's access to clean hydroelectric power presents a unique "green gold" investment prospect.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
CFO Mark Ruus presents Spanish Mountain Gold at VRIC on January 26, 2026 (Duration: 13 minutes)
https://www.youtube.com/watch?v=YzmLGz1Xhhg
Mark Ruus, Chief Financial Officer of Spanish Mountain Gold
Mr. Ruus brings nearly three decades in the mining sector. He began his career at PwC and has since progressed to Vice President and Senior Vice President Tax positions at leading gold mining firms like Kinross Gold Corporation, Goldcorp Inc., and Placer Dome Inc. His experience and CPA - CA qualification underpin his extensive knowledge in financing, cost control, business efficiency, compliance, tax issues, mergers and acquisitions, and financial reporting for domestic and global mining companies.
============================================================================================
Spanish Mountain Gold's Strategic Shift: Auditor Change and Leadership Transition as Catalysts for Growth in 2026
============================================================================================
- Spanish Mountain Gold replaces auditor and appoints new finance director to strengthen governance for 2027 construction decision.
- New auditor BDO and Kim Leroux’s expertise aim to enhance financial oversight and First Nations engagement in British Columbia.
- Operational readiness includes updated resource estimates, 2025 drilling, and XRT technology to optimize gold recovery and reduce carbon footprint.
- Strategic moves address governance risks and sustainability trends, positioning the company to navigate regulatory and market challenges.
The mining sector's transition from exploration to development-stage projects demands robust corporate governance and operational readiness. For Spanish Mountain Gold Ltd., a junior explorer aiming to evolve into an emerging developer, recent strategic moves-namely, a change in auditors and a leadership transition-signal a deliberate effort to align governance and technical capabilities with its 2027 construction decision timeline. These changes, coupled with operational advancements, position the company to navigate the complexities of project development in a resource-constrained and increasingly sustainability-focused industry.
Auditor Change: Strengthening Governance for Development-Stage Rigor
Spanish Mountain Gold's decision to replace Smythe LLP with BDO LLP as its auditor reflects a strategic pivot toward enhanced financial oversight and credibility. According to a report by Business Wire, the Audit Committee selected BDO for its "extensive experience working with mining companies," a critical factor as the firm advances its Spanish Mountain Gold Project toward a build decision. This shift underscores the company's recognition that development-stage projects require auditors with sector-specific expertise to navigate regulatory scrutiny and investor expectations.
The transition also highlights the importance of transparency in capital markets. By filing a Notice of Change of Auditor along with required letters from both the former and successor auditors on SEDAR+, Spanish Mountain Gold has demonstrated compliance with Canadian securities regulations. For investors, this move reduces governance risks associated with inexperienced auditors, a concern that has historically plagued junior miners. BDO's track record in mining audits may also facilitate smoother interactions with lenders and partners, who often demand rigorous financial due diligence before committing to large-scale projects.
Leadership Transition: Kim Leroux's Appointment as a Governance Win
Complementing the auditor change is the appointment of Kim Leroux as Director Finance, effective January 2, 2026. Leroux's background spanning roles at DeBeers and McEwen Mining Inc.-brings a depth of mining finance expertise that aligns with the company's operational ambitions. Notably, her experience in First Nations relationship management adds a critical dimension to corporate governance, particularly in British Columbia, where community engagement is pivotal to project permitting and social license to operate.
The transition from part-time contract CFO Mathew Lee to Leroux's full-time leadership role also addresses a common vulnerability in junior mining firms: inconsistent financial stewardship. By ensuring a seamless handover during Q1 2026, the company minimizes operational disruption while positioning itself to manage the capital-intensive phases of feasibility studies and infrastructure planning. Leroux's focus on "developing and implementing processes and systems" suggests a governance-driven approach to scaling operations, which is essential for attracting institutional investment.
Operational Readiness: Technical and Sustainability-Driven Progress
Beyond governance, Spanish Mountain Gold's operational readiness measures are equally compelling. The completion of a new Mineral Resource Estimate (MRE) and Preliminary Economic Assessment (PEA) by July 2025 provides a data-driven foundation for subsequent feasibility studies. These studies, combined with a 2025 exploration drill program targeting 10,000 meters, aim to de-risk the project by extending mineralization at key targets like Phoenix and K-zone.
Innovation in processing technology further strengthens the company's development-stage preparedness. The exploration of X-ray transmission (XRT) ore sorting-a technique to enhance gold recovery-demonstrates a proactive approach to optimizing project economics according to a Financial Post report. Simultaneously, collaborations with BC Hydro to integrate renewable diesel and electrification initiatives highlight a commitment to reducing the project's carbon footprint, a growing priority for ESG-focused investors. These efforts align with global trends toward decarbonization in mining, potentially improving the project's long-term viability in a regulatory and market landscape increasingly shaped by sustainability metrics.
Strategic Alignment and Future Outlook
Spanish Mountain Gold's dual focus on governance and operational readiness creates a synergistic foundation for its 2027 construction decision. The auditor change and leadership transition address internal capacity constraints, while technical advancements and sustainability initiatives tackle external challenges such as permitting delays and capital cost inflation. For development-stage miners, these factors are often the difference between project success and stagnation.
However, risks remain. The 2025 drill program's results will be critical in validating the MRE's assumptions, and delays in feasibility studies could push the construction decision beyond 2027. Additionally, Leroux's ability to integrate First Nations partnerships into the project's governance framework will determine the speed of regulatory approvals. Investors must monitor these milestones closely, but the company's current trajectory suggests a well-structured path to becoming a producer.
Conclusion
Spanish Mountain Gold's strategic shift in 2026-from auditor and leadership changes to operational innovations-exemplifies how development-stage mining firms can mitigate risks and enhance value. By prioritizing governance rigor and technical preparedness, the company is positioning itself to capitalize on the gold sector's long-term fundamentals while addressing the ESG imperatives of modern capital markets. For investors, the question is no longer whether the project can advance, but how swiftly it can execute its ambitious timeline.
News reference
https://spanishmountaingold.com/news/2025/spa...scal-2025/
==================================
Warrants, Options, Insider share ownership
==================================
https://investorshangout.com/images/MYImages/...302026.jpg
Insider trading transaction record
https://www.barchart.com/stocks/quotes/SPA.VN/insider-trades
https://www.canadianinsider.com/company-insid...cker=SPA.V
==========================================
Mineral Resource Estimate (MRE) as of July 3, 2025
==========================================
https://investorshangout.com/images/MYImages/...timate.png
Resources in the high grade K-zones are not included in the July 3 PEA.
======================================
Unofficial gold resources estimate in the K-zone
======================================
As of February 26,2026
https://investorshangout.com/images/MYImages/...K-zone.jpg
Drilling area:
https://investorshangout.com/images/MYImages/...argets.png
Based on the updated assays in the K-zone and based on the silver resource to gold resource ratio of 1.5 in the Main Zone, if the tonnage in the K-zone is at least 200 million tonnes as in the Main zone, K-zone will has Measured + Indicated resources of 5 million ounces gold and 7 million ounces silver added to the July 3, 2025 PEA.
2026 new PEA's new MRE will show gold and silver Measured + Indicated resources (Proven Reserve) of 9 million ounces of gold and 13 million ounces of silver. If it will be a reality, share price will be very explosive.
2025 drilling consistently intersecting long intervals of high grade gold could be an indication that they are drilling close to the network of gold veins where the placer gold originated as some of the gold veins disintegrated and the gold fragments corroded into fine placer gold by weathering over millions of years. There could still be intact gold veins in SMG's 135 square kilometer property to be discovered. Including the high grade gold in future PEA will significantly reduce capital expenditure and increase gold productivity.
The term "high grade" is relative to the deposit style. The Spanish Mountain project is primarily a large-scale, open-pit, bulk-tonnage project, where the average grades are generally lower compared to narrow-vein underground mines. In this context, grades approaching or exceeding 1 g/t over significant widths are considered "higher-grade" and economically significant for the project's development, especially for the early years of the mine life. The company is also investigating ore sorting technology to potentially increase the processed grade and enhance project economics.
==================================
Charts - Gold, Silver, XAU, SPA.V, SPAUF
==================================
Gold Price - weekly (price updated at End Of Day)
https://stockcharts.com/h-sc/ui?s=$GOLD&p...e_vignette
50-year gold price
https://mrci.com/pdf/gc.pdf
Silver Price - weekly (price updated at End Of Day)
https://stockcharts.com/h-sc/ui?s=$SILVER&...e_vignette
50-year silver price (price in cents)
https://mrci.com/pdf/si.pdf
XAU weekly
https://stockcharts.com/h-sc/ui?s=%24XAU&...9099899440
SPA.V weekly
https://stockcharts.com/h-sc/ui?s=SPA.V&p...e_vignette
SPA.V News, trade data
https://www.stockwatch.com/Quote/Detail.aspx?C:SPA.V
SPAUF.OTCQB weekly
https://stockcharts.com/sc3/ui/?s=SPAUF&p...e_vignette
SPAUF Level 2
https://www.otcmarkets.com/stock/SPAUF/overview
S3Y.FSE
https://ca.finance.yahoo.com/quote/S3Y.F/char...NlcyI6e319
===============
Technical Analysis
===============
https://investorshangout.com/images/MYImages/...SPA.VM.jpg
https://investorshangout.com/images/MYImages/...alysis.png
https://investorshangout.com/images/MYImages/...alysis.png
SPA.V weekly
https://stockcharts.com/sc3/ui/?s=SPA.V&p...8609492691
Case history of bullish Head & Shoulder
https://investorshangout.com/images/MYImages/...istory.png
====================================
Production infrastructure build financing plans
====================================
Gold price
OPTION 1 - Joint venture with a cash rich mining company
OPTION 2A - Debt financing (With XRT ore sorting technology)
https://investorshangout.com/images/MYImages/...ology).jpg
OPTION 2B - Debt financing (No XRT ore sorting technology, process all rocks)
https://investorshangout.com/images/MYImages/...ology).jpg
OPTION 3 - Buyout deal
========================================
Historical buyout deals in the Golden Triangle, BC
========================================
Placer Dome and International Corona acquired Stikine Resources at Can$67 per share
https://www.northernminer.com/news/placer-sta...000178407/
Imperial Metals acquired American Bullion Minerals Ltd. at Can$2.45 a share
https://imperialmetals.com/for-our-shareholde...an-bullion
Newmont acquired GT Gold at $3.25 per share in a Can$393 million deal
https://www.newmont.com/investors/news-releas...fault.aspx
Australian gold and copper producer Newcrest Mining acquired Pretium Resources in a Can$3.84 billion, $18.5 per share deal
https://magazine.cim.org/en/news/2021/newcres...e%20region
In Ontario, Kinross acquired Great Bear Resources for $32 a share in the $1.8 billion deal
https://www.globalminingreview.com/finance-bu...resources/
====================================================
Preliminary Economic Assessment and NI-43-101 Technical Report
====================================================
https://investorshangout.com/images/MYImages/...67_PEA.png
Preliminary Economic Assessment Economics
https://spanishmountaingold.com/project/preli...economics/
August 18, 2025 - NI-43-101 Technical Report
https://spanishmountaingold.com/site/assets/f...-final.pdf
===================================
All-In-Sustaining-Cost of 25 gold producers
===================================
https://www.mining.com/wp-content/uploads/202...31425A.gif
What is All In Sustaining Costs (AISC)?
All-in Sustaining Costs (AISC) in the mining industry, particularly for gold, includes all operating costs, sustaining capital expenditures, and other costs associated with maintaining current production. This includes cash costs, sustaining capital expenditures, general and administrative (G&A) expenses, and environmental and closure costs.
Breakdown on AISC:
Cash Costs:
These are the direct costs of mining and processing, including labor, energy, consumables, and royalties (net of by-product credits).
Sustaining Capital Expenditures:
These are investments required to maintain current production levels, such as equipment replacement, mine development, and other costs to keep the mine operating at its current capacity.
General and Administrative (G&A) Expenses:
These are the costs associated with running the corporate office and other administrative functions that support the mine's operations.
Environmental and Closure Costs:
These include costs related to environmental remediation and mine closure, such as reclamation and decommissioning.
Exploration Expenses (Sustaining):
These are exploration costs that are needed to maintain current production levels and replace depleted resources.
AISC is a comprehensive metric designed to provide a more complete picture of the total cost of mining an ounce of gold, beyond just the direct cash costs.
===============================
Key Steps Leading to a Build Decision
===============================
Spanish Mountain Gold has indicated that production infrastructure construction decision will be made in 2026, after which a two-year construction phase will begin. This timeline allows for the completion of the ongoing drill program, a new Mineral Resource Estimate (MRE) and a new Preliminary Economic Assessment (PEA) in the second half of 2026, as well as securing all necessary reports and approvals to advance development of the project. The new PEA and MRE are crucial steps in optimizing the project for construction. Completing all technical reports and regulatory approvals is a necessary part of the process before the build decision can be made.
========
Overview
========
A mining project can pay loans before achieving revenue by using alternative financing like stream financing, royalty financing, or joint ventures, which are less restrictive than traditional debt and use future production or revenue as collateral instead of pre-existing income. Other methods include securing government grants and incentives, pre-selling a portion of future production through off-take agreements, and raising equity capital through share issues.
===========================
Pre-Revenue Financing Methods
===========================
Streaming Agreements: A company provides upfront capital in exchange for a percentage of the mine's future mineral production, often at a discounted price, according to Stikeman Elliott.
Royalty Financing: A financier funds a project in return for a share of the project's future revenue or profits, which can be seen as an endorsement of the project's potential, says Stikeman Elliott and Lexology.
Joint Ventures: Partnering with other mining companies or investors allows costs to be shared, spreading the financial burden, notes www.altfin.net.
Off-take Agreements: Pre-selling a portion of the future mineral output to buyers can secure upfront financing and provide lenders with confidence in the project's potential.
Government Funding: Governments and development banks sometimes offer grants, loans, or tax incentives for projects aligned with economic or environmental goals, according to www.altfin.net.
Equity Financing: Raising capital by issuing shares is often considered the simplest path for early-stage projects, as it avoids the complexities and strict requirements of debt financing.
Benefits of These Approaches
Non-Dilutive (for streams/royalties): These options don't dilute the original shareholders' equity in the company, notes Stikeman Elliott.
Flexible Terms: Stream and royalty structures can be more flexible and less restrictive than traditional bank debt, allowing for customized repayment profiles, according to Appian Capital Advisory LLP.
Market Confidence: Agreements like streaming and royalties can be seen as a market endorsement of the project, potentially leading to increased investor confidence.
===================
Promise for profitability
===================
Spanish Mountain Gold shows promise for profitability due to a recently updated Preliminary Economic Assessment (PEA) indicating strong economics with a base case NPV5% of C$1.0 billion and an IRR of 18.2%, potentially improving to C$2.3 billion NPV5% and 32.0% IRR with higher gold prices. The project's conventional open-pit, milling operation, access to infrastructure, and new management team with experience in construction and operations contribute to its potential success, although the company is still in the early development stages.
Factors supporting profitability:
Favorable Economics: The PEA projects significant financial returns, with an after-tax Net Present Value (NPV) of C$1.0 billion and an Internal Rate of Return (IRR) of 18.2% at a base gold price of US$2,450/oz, and even better results at a spot price of US$3,300/oz gold.
Strong Resource Confidence: The economic analysis is based on a high degree of resource confidence, incorporating measured and indicated resources, which are key to a successful mining project.
Experienced Management: A new board and management team, brought in since 2022, possess decades of experience in project management, construction, and operations, positioning the company for a production decision.
Developed Infrastructure: The project will benefit from established infrastructure in central British Columbia, including road access and proximity to the city of Williams Lake, reducing operational complexities and costs.
Strategic Project Design: The company plans a conventional open-pit and milling operation, which is a low-risk approach that is less complex than underground mining.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
https://investorshangout.com/images/MYImages/...uction.jpg
簡體中文
==============
最新消息发布
=============
2026年3月2日 - 西班牙山黄金 Phoenix 矿床颗粒矿石分选结果积极,凸显产量提升潜力
https://www.stockwatch.com/News/Item/Z-C!SPA-3791171/C/SPA
基于 Phoenix 矿床样品测试的X射线透射(XRT)结果显示,通过大量剔除废料和低品位矿石(约占进料质量的50%至70%),矿石品位有望提升至样品品位的两倍甚至更高。颗粒矿石分选后,样品中黄金的回收率达到85%至92%。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
2026年2月27日 - 西班牙山黄金 (TSX-V: SPA)(FSE: S3Y)(OTCQB: SPAUF)欣然宣布已与 Metso Canada Inc.(“Metso”)签署了一份谅解备忘录(“MoU”),该公司正朝着推进其西班牙山金矿(“SMG”)项目的可行性和许可迈进。 SMG项目位于加拿大不列颠哥伦比亚省的卡里布区走廊。
https://www.stockwatch.com/News/Item/Z-C!SPA-3790618/C/SPA
==========================================
西班牙山黄金 正在逐步接近可行性和矿山建设决策
==========================================
Metso Canada 服务(视频)
https://www.youtube.com/watch?v=wgiF9uZqDsE
https://www.metso.com/corporate/sustainabilit...-offering/
Metso Canada(前称Metso Outotec) 是一家技术供应商,为提供多家公司采矿设备例如破碎机和磨机, 包括位于 British Columbia Cariboo 地区 的 Blackwater Mine。作为一家全球领先的工业公司,美卓在骨料、矿物加工和金属精炼行业的可持续技术、端到端解决方案和服务方面处于领先地位。该公司致力于通过其产品提高客户的能源和水资源利用效率,提升生产率并降低环境风险。破碎、筛分和研磨是其核心业务。
Metso业务的关键方面:
骨料:为采石和建筑行业提供破碎和筛分设备(移动和固定)。
矿物加工:提供采矿技术,包括磨矿机、分离、过滤和尾矿管理。
金属精炼:提供金属加工解决方案。
服务与磨损件:提供广泛的售后服务、备件和磨损件,以优化设备性能。
可持续性:专注于“积极地球”解决方案,旨在减少客户运营中的能源和水消耗。
==============================================
西班牙山黄金 -- 展望未来 ( 追随Blackwater Mine 的足迹 )
==============================================
Blackwater Mine - Artemis Gold 拥有,位于西班牙山黄金 以西250公里,Prince George 以西南160公里。
https://www.google.ca/maps/place/Blackwater+M...FQAw%3D%3D
Artemis Gold 股价 (ARTG.V)
https://stockcharts.com/sc3/ui/?s=ARTG.V&...8838982129
矿山建设于2023年开始,并在22个月后完成,金银冶炼将在2025年初开始。 作为加拿大最大的黄金开发项目之一,它是一个100%电气化的设施,旨在成为一个低排放的露天矿。 它于2025年5月30日正式开业。
Metso(前身为Metso Outotec)交付了一台Superior MK-III 4265初级旋回破碎机、Nordberg HP900圆锥破碎机和一台14MW球磨机。
设备合同是通过Sedgman Canada Limited促成的,该公司负责工程、采购和施工的管理。
随后的湿法厂(磨矿和CIL工艺)将运营从建设阶段转变为生产阶段。
该地点设有一个完全电气化的加工设施、一条225千伏的输电线和一个重要的尾矿储存设施。
该项目雇用了超过400人,其中有很高比例的本地和土著代表。
2025年12月,阿尔忒弥斯黄金公司批准了一项14.4亿美元的二期扩建计划,以增加产量。 建设计划在2026年第三季度开始,预计在2028年第三季度完成。 扩建旨在提高加工能力,使其跻身加拿大最大的金矿之列。
设计时考虑了低碳足迹,用电动设备替代传统燃料进行采矿和加工。
这是一个露天金银矿,矿山寿命为22年,矿厂处理量为每天16,000吨,6年后可扩展至每天33,000吨,11年后可扩展至每天55,000吨。 它拥有800万盎司的黄金、6220万盎司的白银的探明储量,以及1170万盎司的黄金、1.224亿盎司的白银的可能资源。
=======================
Blackwater Mne - 资本支出
=======================
加拿大 British Columbia 的 Blackwater Mine 第一阶段的初始资本支出(CAPEX)预计在 $730 million 加元 至 $750 million 加元之间。 截至2023年12月31日,约 $389 million 加元的初始资本已被支出,其中 84% 的指导范围下限($615 million 加元)已合同承诺。
剩余资本支出: 截至2024年3月31日,第一阶段剩余的资本支出估计在 $207 million 至 227 million 加元之间。
范围:第一阶段集中于建设一个露天矿和一个年处理能力为 6 million 吨的加工设施。
后续第一阶段升级(“第一阶段A”)
2025年9月,Artemis Gold宣布计划升级第一阶段处理厂(称为第一阶段A),目标是在2026年第四季度之前将产能从每年 6 million 吨提高到 8 million 吨。
第一阶段A资本成本:估计为 $100 million 至 $110 million 加元,由运营现金流资助。
目标:在利用建设第一阶段的现有团队的同时,提高产量和效率。
Artmis Gold 的 Blackwater Mine 第二阶段(EP2)扩建预计将耗资 $1.44 billion 加元,旨在将处理能力扩展到每年 21 million 吨。 预计将在2028年左右完成,这一扩展将主要通过运营现金流来资助,目标是每年生产超过 500,000 盎司的黄金。
================================
Blackwater Mine - 平均金品位和银品位
================================
前五年:平均金品位 1.29 克/吨。
后十七年:平均金品位 0.75 克/吨。
银品位:预计矿山寿命期内平均银品位为 5.78 克/吨。
储量:探明和概略储量总计估计为 334.3 million 吨,金品位 0.75 克/吨,含金量 8 million 盎司;银品位 5.8 克/吨,含银量 62 million 盎司。
前五年平均年产量:黄金 463,000 盎司,白银 1.9 million 盎司
Blackwater Mine 建设视频
1) 2025年2月 - 空中巡游
https://www.youtube.com/watch?v=ndcRuX42b3U
2) 2025年2月 - 矿业技术
https://www.youtube.com/watch?v=8WfAvX_Nzb4
3) 2025年2月 - 健康与安全
https://www.youtube.com/watch?v=ELbEBpNQMAw
4) 2025年2月 - 完工
https://www.youtube.com/watch?v=fpl3Vjd9slM
5) 2025年4月 - 首次黄金浇铸于2025年1月进行
https://www.youtube.com/watch?v=E9nFlVjKIe4
6) 2025年5月30日 - 开幕式
https://www.youtube.com/watch?v=MOXjjZcGdYw
7) 2025年12月 - 第二阶段:生产扩展
https://www.youtube.com/watch?v=R7xr4kidz4I
===========================================
西班牙山黄金 - 通过 Gibraltar Mines 的一生未来展望
===========================================
https://www.youtube.com/watch?v=yJmanh1uQMQ
Gibraltar Mines - 隶属于 Taseko Mines, 位于西班牙山金矿以西50公里处
https://www.google.ca/maps/place/Gibraltar+Mi...FQAw%3D%3D
Gibraltar Mines 是加拿大第二大露天铜钼矿,其主要资源为低品位斑岩型铜钼矿床,矿物成分包括黄铜矿、辉钼矿、斑铜矿和赤铜矿。截至2024年12月31日,该矿拥有6.16亿吨矿石,铜品位为0.26%,钼品位为0.008%。
https://stockcharts.com/sc3/ui/?s=TKO.TO&...5512188236
=========
公司介绍
=========
https://spanishmountaingold.com/investors/presentations/
=====================
西班牙山黄金 - 运营更新
=====================
2024年和2025年的勘探钻探计划发现了提高矿产资源平均品位并可能增加矿坑内及附近资源量的机会。
公司目前的战略重点仍然是优化、降低风险并推进其西班牙山金矿项目,力争在 2027 年底前做出建设决策。
公司已与 ABH Engineering Inc. 合作启动颗粒矿石分选项目,并与 OrePortal Technologies Ltd. 合作开展散装矿石分选研究。
如果 XRT 矿石分选项目成功实施,资本支出将减少,而未来的黄金产量将提高。
2025年8月27日,该公司完成了 $7,199,968 的股权融资。 ( https://spanishmountaingold.com/news/2025/spa...placement/ ). 这笔资金足以支持秋季钻探计划、可行性研究和矿石分选计划,直至2026年。首席执行官彼得·马赫表示,未来的融资将采用非稀释性方式。
认股权证融资:行使面值分别为 $0.25 和 $0.18 的未行使认股权证(分别于 2026 5月31日 和 11月15日 到期)将在 2026 年为国库带来 $10.9 million,有助于资助该项目的进展。
摘自2024年5月31日的融资协议:“每股面值 $0.25 的认股权证将于2026年5月30日到期。每份认股权证赋予持有人自发行之日起24个月内以每股 $0.25 的价格购买一股额外股份(“认股权证股份”)的权利,但如果10日成交量加权平均价格超过每股 $0.30,则认股权证提前到期"。
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...3-million/
公司已聘请领先的企业赞助研究公司 Atrium Research Corporation 提供服务。Atrium 将为公司提供一系列研究服务,并向潜在投资者介绍公司的投资价值。Atrium 还将安排公司管理团队接受视频采访,以访谈形式阐述投资价值。
Atrium Research 将 SPA.V 的目标股价上调至 $0.80
https://www.atriumresearch.ca/spa
目前的勘探鑽探化驗結果持續顯示,在新劃定的 Orca 斷層靶區內,沿走向長度超過300公尺處存在顯著的高品位礦化,且該礦化帶已在兩個平行相鄰的鑽孔剖面上連續延伸。鑽孔 25-DH-1299 的深部交匯處,金品位為 1.67 克/噸,厚度為 45.54 米,位於 2025 年礦產資源估算 (MRE) 的約束露天礦坑邊界之下,證實了歷史鑽探結果,即深處存在更高品位的礦產化,並強調需要進行更深層的探礦潛力。
2025年7月3日完成的初步经济评估和NI-43-101技术报告将为2026年开展新的初步经济评估和矿产资源评估奠定基础。届时,将在高品位K区和凤凰区探明更多金矿资源后,启动露天矿坑作业。公司将启动新的预可行性研究(PFS),或可能直接进入可行性研究(FS)。
==========
未来展望
==========
西班牙山黄金 市值远低于同行。分析师给出的目标价表明该公司被低估,具有巨大的增长潜力, 原因包括即将发布的资源量更新报告、潜在的高品位矿藏发现,以及利用现有水力发电资源开发独特的“绿色黄金”机遇。
即将到来的催化剂:新的初步经济评估和资源估算预计将重新评估该股的价格。
矿化潜力:该项目拥有覆盖广泛、品位高的矿化带,表明未来存在发现金矿的潜力。
绿色黄金机遇:该公司拥有清洁水力发电的渠道,为其带来了独特的“绿色黄金”投资前景。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
首席财务官 Mark Ruus 介绍 Spanish Mountain Gold 2026 年 1 月 26 日在 VRIC 举办(时长:13 分钟)
https://www.youtube.com/watch?v=YzmLGz1Xhhg
Mark Ruus 在矿业领域拥有近三十年的从业经验。他最初在普华永道 (PwC) 工作,之后在金罗斯黄金公司 (Kinross Gold Corporation)、戈尔德科公司 (Goldcorp Inc.) 和普莱塞穹顶公司 (Placer Dome Inc.) 等领先的黄金矿业公司担任副总裁和高级副总裁税务职位。他丰富的经验和注册会计师 (CPA-CA) 资格,使其在国内外矿业公司的融资、成本控制、业务效率、合规、税务问题、并购和财务报告方面拥有广泛的知识。
===============================================================
西班牙山黄金 的战略转变:审计师更换和领导层过渡作为2026年增长的催化剂
===============================================================
- 西班牙山金矿更换审计师并任命新财务总监,以加强2027年建设决策的治理
- 新审计师BDO和Kim Leroux的专业知识旨在加强不列颠哥伦比亚省的财务监督和原住民参与。
- 运营准备包括更新的资源估算、2025年的钻探以及XRT技术,以优化黄金回收并减少碳足迹。
- 战略举措应对治理风险和可持续发展趋势,使公司能够应对监管和市场挑战。
采矿行业从勘探阶段过渡到开发阶段项目需要强有力的公司治理和运营准备。 对于西班牙山金业有限公司(Spanish Mountain Gold Ltd.)来说,这家初级勘探公司旨在发展成为新兴开发商,最近的战略举措——即更换审计师和领导层过渡——表明其有意努力将治理和技术能力与2027年的建设决策时间表对齐。 这些变化,加上运营方面的进展,使公司能够在资源受限且日益注重可持续发展的行业中,驾驭项目开发的复杂性。
审计师更换:加强发展阶段的治理严谨性
西班牙山金矿决定将Smythe LLP更换为BDO LLP作为其审计师,反映出其在财务监督和信誉方面的战略转变。 根据Business Wire的一份报告,审计委员会选择了BDO,因为其“在与矿业公司合作方面拥有丰富经验”,这是该公司在推进其西班牙山金矿项目至建设决策时的一个关键因素。 这一转变突显了公司认识到开发阶段项目需要具备行业专业知识的审计师,以应对监管审查和投资者期望。
这一过渡也突显了资本市场透明度的重要性。 通过在SEDAR+上提交更换审计师通知以及前任和继任审计师的必要函件,Spanish Mountain Gold展示了其遵守加拿大证券法规的合规性。 对于投资者来说,这一举措减少了与缺乏经验的审计师相关的治理风险,这是历史上困扰初级矿业公司的一个问题。 BDO在矿业审计方面的良好记录也可能促进与贷款人和合作伙伴的更顺畅互动,这些贷款人和合作伙伴在承诺大型项目之前通常要求进行严格的财务尽职调查。
领导层过渡:金·勒鲁的任命是治理的胜利
与审计师更换相辅相成的是金·勒鲁(Kim Leroux)被任命为财务总监,任命将于2026年1月2日生效。 Leroux在DeBeers和McEwen Mining Inc.的背景带来了深厚的矿业金融专业知识,这与公司的运营目标相一致。 值得注意的是,她在第一民族关系管理方面的经验为公司治理增添了一个关键维度,特别是在不列颠哥伦比亚省,在那里社区参与对项目许可和社会运营许可证至关重要。
从兼职合同首席财务官Mathew Lee过渡到Leroux的全职领导角色,也解决了初级矿业公司常见的一个弱点:财务管理不一致。 通过确保在2026年第一季度进行无缝交接,公司在最小化运营中断的同时,也为管理资本密集型的可行性研究和基础设施规划阶段做好了准备。 勒鲁对“开发和实施流程和系统”的关注表明了一种以治理为驱动的扩展运营的方法,这对于吸引机构投资至关重要。
运营准备:技术和可持续性驱动的进展
除了治理之外,Spanish Mountain Gold 的运营准备措施同样引人注目。 到2025年7月完成新的矿产资源估算(MRE)和初步经济评估(PEA)为后续的可行性研究提供了数据驱动的基础。 这些研究结合了2025年的勘探钻探计划,目标是10,000米,旨在通过在凤凰区和K区等关键目标地延伸矿化来降低项目风险。
加工技术的创新进一步增强了公司在开发阶段的准备。 根据《金融邮报》的报道,探索X射线透射(XRT)矿石分选技术——一种提高黄金回收率的技术——展示了优化项目经济性的积极方法。 同时,与BC Hydro的合作整合可再生柴油和电气化举措,突显了减少项目碳足迹的承诺,这已成为以ESG为重点的投资者日益关注的优先事项。 这些努力与全球矿业去碳化的趋势相一致,可能会在一个日益受到可持续性指标影响的监管和市场环境中,改善项目的长期可行性。
战略对齐与未来展望
西班牙山金矿公司在治理和运营准备方面的双重关注为其2027年的建设决策奠定了协同基础。 审计师更换和领导层过渡解决了内部能力限制,而技术进步和可持续发展举措则应对了外部挑战,如许可延误和资本成本通胀。 对于处于开发阶段的矿业公司来说,这些因素往往是项目成功与停滞之间的关键区别。
然而,风险仍然存在。 2025年的钻探计划结果将对验证矿产资源估算(MRE)的假设至关重要,而可行性研究的延迟可能会将建设决策推迟到2027年以后。 此外,Leroux将原住民合作伙伴关系整合到项目治理框架中的能力将决定监管审批的速度。 投资者必须密切关注这些里程碑,但公司的当前轨迹表明其成为生产商的道路结构良好。
结论
西班牙山金矿在2026年的战略转变——从审计和领导层变动到运营创新——展示了开发阶段的矿业公司如何减轻风险并提升价值。 通过优先考虑治理严格性和技术准备,公司正在为利用黄金行业的长期基本面做好准备,同时应对现代资本市场的ESG要求。 对于投资者来说,问题不再是项目能否推进,而是它能多快执行其雄心勃勃的时间表。
新闻参考
https://spanishmountaingold.com/news/2025/spa...scal-2025/
====================================
截至2025年7月3日的矿产资源量估算 (MRE)
====================================
https://investorshangout.com/images/MYImages/...timate.png
高品位K区矿床的资源量未包含在7月3日的初步经济评估 (PEA) 中。
=========================
K区非官方估算的黄金资源量
=========================
截至2月26日
https://investorshangout.com/images/MYImages/...K-zone.jpg
钻井区域:
https://investorshangout.com/images/MYImages/...argets.png
根据 K 区更新的化验结果,以及主矿区白银资源量与黄金资源量之比为 1.5,如果K区的吨位至少达到2亿吨,与主区相同,K 区在 2025 年 7 月 3 日的初步经济评估中将新增 5 million 盎司黄金和 7 million 盎司白银的探明 + 指示资源量。
2026 年新的初步经济评估报告 (PEA) 的新矿产资源估算报告 (MRE) 将显示已探明和已指示的黄金和白银资源量(已证实储量)分别为 9 million 盎司黄金和 13 million 盎司白银。如果此事成真,股价将会出现爆炸式增长。
2025年的钻探工作持续发现长段高品位金矿表明我们钻探的区域可能靠近金矿脉网络,而砂金的来源正是这些金矿脉。这些金矿脉在两亿年的风化作用下崩解,可见的金被腐蚀成细小的砂金。将高品位金矿纳入未来的初步经济评估将显著改善项目的经济效益。
“高品位”一词的含义取决于矿床类型。西班牙山项目主要是一个大型露天矿项目,其矿石品位通常低于窄脉地下矿。在此背景下,品位接近或超过1克/吨且矿体宽度较大的矿石被视为“高品位”,对项目开发具有重要的经济意义,尤其是在矿山运营初期。公司目前也在研究矿石分选技术,以期提高矿石品位,从而提升项目经济效益。
===================================
图表 - 黄金、白银、XAU、SPA.V、SPAUF
===================================
黄金价格 周线图 (价格仅在每日收盘时更新)
https://stockcharts.com/h-sc/ui?s=$GOLD&p...e_vignette
50 年黄金价格
https://mrci.com/pdf/gc.pdf
白银价格 周线图 (价格仅在每日收盘时更新日)
https://stockcharts.com/h-sc/ui?s=$SILVER&...e_vignette
50年白银价格 (价格单位:美分)
https://mrci.com/pdf/si.pdf
矿业指数 (XAU) 周线图
https://stockcharts.com/h-sc/ui?s=%24XAU&...9099899440
SPA.V 周线图
https://stockcharts.com/h-sc/ui?s=SPA.V&p...e_vignette
SPA.V - 新闻、交易数据
https://www.stockwatch.com/Quote/Detail.aspx?C:SPA.V
SPAUF.OTCQB 周线图
https://stockcharts.com/sc3/ui/?s=SPAUF&p...e_vignette
SPAUF 二级
https://www.otcmarkets.com/stock/SPAUF/overview
S3Y.FSE
https://ca.finance.yahoo.com/quote/S3Y.F/char...NlcyI6e319
=========
技术分析
=========
https://investorshangout.com/images/MYImages/...SPA.VM.jpg
https://investorshangout.com/images/MYImages/...alysis.png
https://investorshangout.com/images/MYImages/...alysis.png
SPA.V weekly
https://stockcharts.com/sc3/ui/?s=SPA.V&p...8609492691
看涨头肩形态案例
https://investorshangout.com/images/MYImages/...istory.png
=========
勘探潜力
=========
西班牙山黄金公司近期钻探工作持续发现长段金矿化,其中包括显著的高品位矿段,其品位通常高于项目整体平均品位。公司正重点勘探并确认这些高品位矿化区域,以期提升项目经济效益。
金品位及矿段详情
项目整体品位:2025年初步经济评估(PEA)中,已探明和已控制矿产资源的平均品位约为0.44克/吨。
高品位矿段:近期勘探钻探计划旨在确定可纳入未来矿山规划的高品位矿化带。这些勘探项目已取得多个显著的高品位矿段:
其中一个钻孔截获了123.00米、平均金品位为1.08克/吨的矿段,其中包括一段47.28米、平均金品位为2.29克/吨的高品位矿段。
另一个钻孔截获了一段107.50米、平均金品位为0.68克/吨的矿段,其中包括一段41.00米、平均金品位为0.98克/吨的矿段。
钻探还证实,在一段更宽的96.47米、平均金品位为0.91克/吨的矿段内,存在一段29.00米、平均金品位为2.55克/吨的连续高品位矿段。
在新的 Orca 断层区域进行的近地表钻探也显示出多处长截矿段,例如35.80米、金品位1.18克/吨和41.00米、金品位0.98克/吨。
“高品位”的定义
“高品位”一词与矿床类型相关。西班牙山项目主要是一个大型露天矿项目,其平均品位通常低于窄脉地下矿。在此背景下,品位接近或超过1克/吨且矿体宽度较大的矿段被认为是“高品位”,对项目的开发具有重要的经济意义,尤其是在矿山运营初期。公司还在研究矿石分选技术,以期提高矿石品位并改善项目经济效益。
=======================
认股权证、期权、内部股权
=======================
https://investorshangout.com/images/MYImages/...302026.jpg
内幕交易更新
https://www.barchart.com/stocks/quotes/SPA.VN/insider-trades
https://www.canadianinsider.com/company-insid...cker=SPA.V
========================
生产基础设施建设融资计划
========================
黄金价格
方案 1 - 与一家资金雄厚的矿业公司合资
方案 2A - 债务融资 (采用XRT选矿技术)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 2B - 债务融资 (无XRT选矿技术,处理所有岩石)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 3 - 收购交易
British Columbia Golden Triangle 地区的历史收购交易
Placer Dome 和 International Corona 以每股 $67 收购 Stikine Resources
https://www.northernminer.com/news/placer-sta...000178407/
Imperial Metals 以每股 $2.45 收购 American Bullion Minerals Ltd.
https://imperialmetals.com/for-our-shareholde...an-bullion
Newmont 以每股 $3.25 收购 GT Gold,交易金额达 $393 million
https://www.newmont.com/investors/news-releas...fault.aspx
澳大利亚黄金和铜生产商 Newcrest Mining 以 每股 $18.5 价格收购 Pretium Resources,交易金额达 $3.84 billion
https://magazine.cim.org/en/news/2021/newcres...e%20region
在 Ontario, Kinross 以 每股 $32 收购 Great Bear Resources, 交易金额达 $1.8 billion
https://www.globalminingreview.com/finance-bu...resources/
==============================
初步经济评估及 NI-43-101 技术报告
==============================
https://investorshangout.com/images/MYImages/...67_PEA.png
初步经济评估 (Preliminary Economic Assessment Economics)
https://spanishmountaingold.com/project/preli...economics/
August 18, 2025 - NI-43-101 技术报告 (Technical Report)
https://spanishmountaingold.com/site/assets/f...-final.pdf
===========================
25家金矿生产商的总体维持成本
===========================
https://www.mining.com/wp-content/uploads/202...31425A.gif
什么是总维持成本 (AISC)?
采矿业(尤其是黄金行业)的总维持成本 (AISC) 包括所有运营成本、维持性资本支出以及维持当前生产相关的其他成本。这包括现金成本、维持性资本支出、一般及行政管理 (G&A) 费用以及环境成本和矿场关闭成本。
总维持成本明细:
现金成本:
这些是采矿和加工的直接成本,包括劳动力、能源、消耗品和特许权使用费(扣除副产品抵扣)。
持续性资本支出:
这些是维持当前生产水平所需的投资,例如设备更换、矿山开发以及维持矿山当前产能所需的其他成本。
一般及行政管理 (G&A) 费用:
这些是与运营公司办公室和其他支持矿山运营的行政职能相关的成本。
环境及关闭成本:
这些包括与环境修复和矿山关闭相关的成本,例如复垦和退役。
勘探费用(维持性):
这些是维持当前生产水平和替换枯竭资源所需的勘探成本。
总维持成本 (AISC) 是一项综合指标,旨在更全面地反映开采一盎司黄金的总成本,而不仅仅是直接现金成本。
=====================
促成建造决策的关键步骤
=====================
西班牙山黄金 表示,生产基础建设会在 2026年做出决定,之后将开始进入为期两年的建设阶段。这一时间安排确保了正在进行的钻探计划、新的矿产资源估算(MRE)和新的初步经济评估(PEA)在2026年下半年完成,以及所有推进项目开发所需的报告和审批手续的顺利取得。新的PEA和MRE是优化项目建设的关键步骤。在做出建设决定之前,完成所有技术报告和监管审批是必要环节。
======
概述
======
矿业项目可以通过替代融资(例如流融资、矿权使用费融资或合资企业)在实现收入之前偿还贷款。这些融资方式的限制比传统债务更少,并且可以使用未来产量或收入作为抵押品,而不是现有收入。其他方法包括获得政府补助和奖励、通过包销协议预售部分未来产量,以及通过发行股票筹集股本。
==============
收入前融资方法
==============
流式协议:据 Stikeman Elliott 称,一家公司提供前期资本,以换取矿山未来矿产产量的一定比例,通常以折扣价出售。
特许权使用费融资:据 Stikeman Elliott 和 Lexology 称,融资方为项目提供资金,以换取项目未来收入或利润的一部分,这可以被视为对项目潜力的认可。
合资企业:与其他矿业公司或投资者合作可以分摊成本,分散财务负担,www.altfin.net 指出。
包销协议:将未来矿产产量的一部分预售给买家可以获得前期融资,并使贷款方对项目潜力充满信心。
政府资助:据 www.altfin.net 称,政府和开发银行有时会为符合经济或环境目标的项目提供赠款、贷款或税收优惠。
股权融资:通过发行股票筹集资金通常被认为是早期项目最简单的途径,因为它避免了债务融资的复杂性和严格要求。
这些方法的优势:
非稀释性(针对矿流/特许权使用费):Stikeman Elliott 指出,这些选择不会稀释公司原有股东权益。
灵活的条款:Appian Capital Advisory LLP 表示,矿流和特许权使用费结构比传统银行债务更灵活、限制更少,允许定制还款方案。
市场信心:矿流和特许权使用费等协议可被视为市场对项目的认可,从而可能增强投资者信心。
=========
盈利前景
=========
西班牙山地黄金公司 近期更新的初步经济评估 (PEA) 显示其经济前景良好,基准情景下净现值 (NPV) 为 10 亿加元,内部收益率 (IRR) 为 18.2%,随着金价上涨,净现值 (NPV) 和内部收益率 (IRR) 可能分别升至 23 亿加元和 32.0%。尽管该公司仍处于早期开发阶段,但该项目的传统露天开采、铣削作业、基础设施使用权以及具有施工和运营经验的新管理团队为其潜在的成功做出了贡献。
支持盈利能力的因素:
良好的经济效益:初步经济评估 (PEA) 预计,该项目将带来可观的财务回报,税后净现值 (NPV) 为 $1 billion,内部收益率 (IRR) 为 18.2%,基准金价为 2,450 美元/盎司;现货金价为 3,300 美元/盎司时,回报将更加可观。
强大的资源信心:经济分析基于高度的资源信心,涵盖了已探明和已指示的资源量,这些资源量是采矿项目成功的关键。
经验丰富的管理层:自 2022 年起,公司组建了新的董事会和管理团队,在项目管理、建设和运营方面拥有数十年的经验,为公司制定生产决策奠定了基础。
发达的基础设施:该项目将受益于不列颠哥伦比亚省中部完善的基础设施,包括公路交通便利以及毗邻威廉姆斯湖市的优势,从而降低运营复杂性和成本。
战略项目设计:该公司计划采用传统的露天开采和铣削作业,这是一种低风险的方法,比地下采矿更简单。
信息来源
https://spanishmountaingold.com/news/2025/spa...scal-2025/
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
https://investorshangout.com/images/MYImages/...uction.jpg
繁體中文
==============
最新消息發布
=============
2026年3月2日 - 西班牙山黃金 Phoenix 礦床顆粒礦石分選結果積極,凸顯產量提升潛力
https://www.stockwatch.com/News/Item/Z-C!SPA-3791171/C/SPA
基於 Phoenix 礦床樣品測試的X射線透射(XRT)結果顯示,透過大量剔除廢料和低品位礦石(約佔進料品質的50%至70%),礦石品位有望提升至樣品品位的兩倍甚至更高。顆粒礦石分選後,樣品中黃金的回收率達到85%至92%。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
2026年2月27日 - 西班牙山黃金 (TSX-V: SPA)(FSE: S3Y)(OTCQB: SPAUF)欣然宣布已與 Metso Canada Inc.(“Metso”)簽署了一份諒解備忘錄(“MoU”),該公司正朝著推進其西班牙山金礦(“SMG”)項目的可行性和許可邁進。 SMG項目位於加拿大不列顛哥倫比亞省的卡裡布區走廊。
https://www.stockwatch.com/News/Item/Z-C!SPA-3790618/C/SPA
==========================================
西班牙山黃金 正在逐步接近可行性和礦山建設決策
==========================================
Metso Canada 服務(視頻)
https://www.youtube.com/watch?v=wgiF9uZqDsE
https://www.metso.com/corporate/sustainabilit...-offering/
Metso Canada(前稱Metso Outotec) 是一家技術供應商,為提供多家公司採礦設備例如破碎機和磨機, 包括位於 British Columbia Cariboo 地區 的 Blackwater Mine。作為一家全球領先的工業公司,美卓在骨料、礦物加工和金屬精煉行業的可持續技術、端到端解決方案和服務方面處於領先地位。該公司致力於通過其產品提高客戶的能源和水資源利用效率,提升生產率並降低環境風險。破碎、篩分和研磨是其核心業務。
Metso業務的關鍵方面:
骨料:為採石和建筑行業提供破碎和篩分設備(移動和固定)。
礦物加工:提供採礦技術,包括磨礦機、分離、過濾和尾礦管理。
金屬精煉:提供金屬加工解決方案。
服務與磨損件:提供廣泛的售后服務、備件和磨損件,以優化設備性能。
可持續性:專注於“積極地球”解決方案,旨在減少客戶運營中的能源和水消耗。
================================================
西班牙山黃金-展望未來 ( 追隨 Blackwater Mine 的足跡 )
================================================
Blackwater Mine - Artmis Gold 擁有,位於西班牙山黃金 以西250公里,Prince George 以西南160公里。
https://www.google.ca/maps/place/Blackwater+M...FQAw%3D%3D
Artemis Gold 股價 (ARTG.V)
https://stockcharts.com/sc3/ui/?s=ARTG.V&...8838982129
礦山建設於2023年開始,並在22個月后完成,金銀冶煉將在2025年初開始。 作為加拿大最大的黃金開發項目之一,它是一個100%電氣化的設施,旨在成為一個低排放的露天礦。 它於2025年5月30日正式開業。
Metso(前身為Metso Outotec)交付了一台Superior MK-III 4265初級旋回破碎機、Nordberg HP900圓錐破碎機和一台14MW球磨機。
設備合同是通過Sedgman Canada Limited促成的,該公司負責工程、採購和施工的管理。
隨后的濕法廠(磨礦和CIL工藝)將運營從建設階段轉變為生產階段。
該地點設有一個完全電氣化的加工設施、一條225千伏的輸電線和一個重要的尾礦儲存設施。
該項目雇用了超過400人,其中有很高比例的本地和土著代表。
2025年12月,阿爾忒彌斯黃金公司批准了一項14.4億美元的二期擴建計劃,以增加產量。 建設計劃在2026年第三季度開始,預計在2028年第三季度完成。 擴建旨在提高加工能力,使其躋身加拿大最大的金礦之列。
設計時考慮了低碳足跡,用電動設備替代傳統燃料進行採礦和加工。
這是一個露天金銀礦,礦山壽命為22年,礦廠處理量為每天16,000噸,6年后可擴展至每天33,000噸,11年后可擴展至每天55,000噸。 它擁有800萬盎司的黃金、6220萬盎司的白銀的探明儲量,以及1170萬盎司的黃金、1.224億盎司的白銀的可能資源。
=======================
Blackwater Mine -資本支出
=======================
加拿大 British Columbia 的 Blackwater Mine 第一階段的初始資本支出(CAPEX)預計在 $730 million 加元 至 $750 million 加元之間。 截至2023年12月31日,約 $389 million 加元的初始資本已被支出,其中 84% 的指導范圍下限($615 million 加元)已合同承諾。
剩余資本支出: 截至2024年3月31日,第一階段剩余的資本支出估計在 $207 million 至 $227 million 加元之間。
范圍:第一階段集中於建設一個露天礦和一個年處理能力為 6 million 噸的加工設施。
后續第一階段升級(“第一階段A”)
2025年9月,Artemis Gold宣布計劃升級第一階段處理廠(稱為第一階段A),目標是在2026年第四季度之前將產能從每年 6 million 噸提高到 8 million 噸。
第一階段A資本成本:估計為 $100 million 至 $110 million 加元,由運營現金流資助。
目標:在利用建設第一階段的現有團隊的同時,提高產量和效率。
Artemis Gold 的 Blackwater Mine 第二階段(EP2)擴建預計將耗資 $1.44 billion 加元,旨在將處理能力擴展到每年 21 million 噸。 預計將在2028年左右完成,這一擴展將主要通過運營現金流來資助,目標是每年生產超過 500,000 盎司的黃金。
=================================
Blackwater Mine - 平均金品位和銀品位
=================================
前五年:平均金品位 1.29 克/噸。
后十七年:平均金品位 0.75 克/噸。
銀品位:預計礦山壽命期內平均銀品位為 5.78 克/噸。
儲量:探明和概略儲量總計估計為 334.3 million 噸,金品位 0.75 克/噸,含金量 8 million 盎司﹔銀品位 5.8 克/噸,含銀量 62 million 盎司。
前五年平均年產量:黃金 463,000 盎司,白銀 1.9 million 盎司
Blackwater Mine 建設視頻
1) 2025年2月 - 空中巡游
https://www.youtube.com/watch?v=ndcRuX42b3U
2) 2025年2月 - 礦業技術
https://www.youtube.com/watch?v=8WfAvX_Nzb4
3) 2025年2月 - 健康與安全
https://www.youtube.com/watch?v=ELbEBpNQMAw
4) 2025年2月 - 完工
https://www.youtube.com/watch?v=fpl3Vjd9slM
5) 2025年4月 - 首次黃金澆鑄於2025年1月進行
https://www.youtube.com/watch?v=E9nFlVjKIe4
6) 2025年5月30日 - 開幕式
https://www.youtube.com/watch?v=MOXjjZcGdYw
7) 2025年12月 - 第二階段:生產擴展
https://www.youtube.com/watch?v=R7xr4kidz4I
==========================================
西班牙山黃金 - 透過Gibraltar Mines的一生未來展望
==========================================
https://www.youtube.com/watch?v=yJmanh1uQMQ
Gibraltar Mines - 隸屬於 Tasedo Mines,位於西班牙山金礦以西50公裡處
https://www.google.ca/maps/place/Gibraltar+Mi...FQAw%3D%3D
Gibraltar Mines 是加拿大第二大露天銅鉬礦,其主要資源為低品位斑岩型銅鉬礦床,礦物成分包括黃銅礦、輝鉬礦、斑銅礦和赤銅礦。截至2024年12月31日,該礦擁有6.16億噸礦石,銅品位為0.26%,鉬品位為0.008%。
https://stockcharts.com/sc3/ui/?s=TKO.TO&...5512188236
=========
公司介绍
=========
https://spanishmountaingold.com/investors/presentations/
=====================
西班牙山黄金 - 運營更新
=====================
2024年和2025年的勘探鑽探計劃發現了提高礦產資源平均品位並可能增加礦坑內及附近資源量的機會。
公司目前的戰略重點仍然是優化、降低風險並推進其西班牙山金礦項目,力爭在 2027 年底前做出建設決策。
公司已與 ABH Engineering Inc. 合作啟動顆粒礦石分選項目,並與 OrePortal Technologies Ltd. 合作開展散裝礦石分選研究。
如果 XRT 礦石分選項目成功實施,資本支出將減少,而未來的黃金產量將提高。
2025年8月27日,該公司完成了 $7,199,968 股權融資。 ( https://spanishmountaingold.com/news/2025/spa...placement/ ). 這筆資金足以支持秋季鑽探計劃、可行性研究和礦石分選計劃,直至2026年。執行長彼得馬赫表示,未來的融資將採用非稀釋性方式。
認股權證融資:行使面額分別為 $0.25 和 $0.18 的未行使認股權證(分別於 2026 5月31日 和 11月15日 到期)將在 2026 年為國庫帶來 $10.9 million,有助於資助該計畫的進展。
摘自2024年5月31日的融資協議:"每股面額 $0.25 的認股權證將於2026年5月30日到期。每份認股權證賦予持有人自發行日起24個月內以每股 $0.25 的價格購買一股額外股份(“認股權證股份”)的權利,但如果 普通股的10日成交量加權平均價格超過每股 $0.30, 則認股權證提前到期"
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...placement/
https://spanishmountaingold.com/news/2024/spa...3-million/
公司已聘請領先的企業贊助研究公司 Atrium Research Corporation 提供服務。Atrium 將為公司提供一系列研究服務,並向潛在投資者介紹公司的投資價值。Atrium 還將安排公司管理團隊接受視頻採訪,以訪談形式闡述投資價值。
Atrium Research 將 SPA.V 的目標價上調至 $0.80
https://www.atriumresearch.ca/spa
目前的勘探鑽探化驗結果持續顯示,在新劃定的 Orca 斷層靶區內,沿走向長度超過300公尺處存在顯著的高品位礦化,且該礦化帶已在兩個平行相鄰的鑽孔剖面上連續延伸。鑽孔 25-DH-1299 的深部交匯處,金品位為 1.67 克/噸,厚度為 45.54 米,位於 2025 年礦產資源估算 (MRE) 的約束露天礦坑邊界之下,證實了歷史鑽探結果,即深處存在更高品位的礦產化,並強調需要進行更深層的探礦潛力。
2025年7月3日完成的初步經濟評估和NI-43-101技術報告將為2026年開展新的初步經濟評估和礦產資源評估奠定基礎。屆時,將在高品位K區和鳳凰區探明更多金礦資源后,啟動露天礦坑作業。公司將啟動新的預可行性研究(PFS),或可能直接進入可行性研究(FS)。
==========
未來展望
==========
西班牙山黃金 的市值遠低於同業。分析師給出的目標價表明該公司被低估,具有巨大的成長潛力, 原因包括即將發布的資源更新報告、潛在的高品位礦藏發現,以及利用現有水力發電資源開發獨特的「綠色黃金」機會。
即將到來的催化劑:新的初步經濟評估和資源估算預計將重新評估該股的價格。
礦化潛力:該項目擁有覆蓋廣泛、品位高的礦化帶,表明未來存在發現金礦的潛力。
綠色黃金機遇:該公司擁有清潔水力發電的渠道,為其帶來了獨特的“綠色黃金”投資前景。
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
財務長 Mark Ruus 介紹 Spanish Mountain Gold 2026 年 1 月 26 日在 VRIC 舉行(長度:13 分鐘)
https://www.youtube.com/watch?v=YzmLGz1Xhhg
Mark Ruus 在礦業領域擁有近三十年的經驗。他最初在普華永道 (PwC) 工作,之後在金羅斯黃金公司 (Kinross Gold Corporation)、戈爾德科公司 (Goldcorp Inc.) 和普萊塞穹頂公司 (Placer Dome Inc.) 等領先的黃金礦業公司擔任副總裁和高級副總裁稅務職位。他豐富的經驗和註冊會計師 (CPA-CA) 資格,使其在國內外礦業公司的融資、成本控制、業務效率、合規、稅務問題、併購和財務報告方面擁有廣泛的知識。
================================================================
西班牙山黃金 的戰略轉變:審計師更換和領導層過渡作為2026年增長的催化劑
================================================================
- 西班牙山黃金 更換審計師並任命新財務總監,以加強2027年建設決策的治理
- 新審計師BDO和Kim Leroux的專業知識旨在加強不列顛哥倫比亞省的財務監督和原住民參與。
- 運營准備包括更新的資源估算、2025年的鑽探以及XRT技術,以優化黃金回收並減少碳足跡。
- 戰略舉措應對治理風險和可持續發展趨勢,使公司能夠應對監管和市場挑戰。
採礦行業從勘探階段過渡到開發階段項目需要強有力的公司治理和運營准備。 對於西班牙山金業有限公司(Spanish Mountain Gold Ltd.)來說,這家初級勘探公司旨在發展成為新興開發商,最近的戰略舉措——即更換審計師和領導層過渡——表明其有意努力將治理和技術能力與2027年的建設決策時間表對齊。 這些變化,加上運營方面的進展,使公司能夠在資源受限且日益注重可持續發展的行業中,駕馭項目開發的復雜性。
審計師更換:加強發展階段的治理嚴謹性
西班牙山金礦決定將Smythe LLP更換為BDO LLP作為其審計師,反映出其在財務監督和信譽方面的戰略轉變。 根據Business Wire的一份報告,審計委員會選擇了BDO,因為其“在與礦業公司合作方面擁有豐富經驗”,這是該公司在推進其西班牙山金礦項目至建設決策時的一個關鍵因素。 這一轉變突顯了公司認識到開發階段項目需要具備行業專業知識的審計師,以應對監管審查和投資者期望。
這一過渡也突顯了資本市場透明度的重要性。 通過在SEDAR+上提交更換審計師通知以及前任和繼任審計師的必要函件,Spanish Mountain Gold展示了其遵守加拿大証券法規的合規性。 對於投資者來說,這一舉措減少了與缺乏經驗的審計師相關的治理風險,這是歷史上困擾初級礦業公司的一個問題。 BDO在礦業審計方面的良好記錄也可能促進與貸款人和合作伙伴的更順暢互動,這些貸款人和合作伙伴在承諾大型項目之前通常要求進行嚴格的財務盡職調查。
領導層過渡:金·勒魯的任命是治理的勝利
與審計師更換相輔相成的是金·勒魯(Kim Leroux)被任命為財務總監,任命將於2026年1月2日生效。 Leroux在DeBeers和McEwen Mining Inc.的背景帶來了深厚的礦業金融專業知識,這與公司的運營目標相一致。 值得注意的是,她在第一民族關系管理方面的經驗為公司治理增添了一個關鍵維度,特別是在不列顛哥倫比亞省,在那裡社區參與對項目許可和社會運營許可証至關重要。
從兼職合同首席財務官Mathew Lee過渡到Leroux的全職領導角色,也解決了初級礦業公司常見的一個弱點:財務管理不一致。 通過確保在2026年第一季度進行無縫交接,公司在最小化運營中斷的同時,也為管理資本密集型的可行性研究和基礎設施規劃階段做好了准備。 勒魯對“開發和實施流程和系統”的關注表明了一種以治理為驅動的擴展運營的方法,這對於吸引機構投資至關重要。
運營准備:技術和可持續性驅動的進展
除了治理之外,Spanish Mountain Gold 的運營准備措施同樣引人注目。 到2025年7月完成新的礦產資源估算(MRE)和初步經濟評估(PEA)為后續的可行性研究提供了數據驅動的基礎。 這些研究結合了2025年的勘探鑽探計劃,目標是10,000米,旨在通過在鳳凰區和K區等關鍵目標地延伸礦化來降低項目風險。
加工技術的創新進一步增強了公司在開發階段的准備。 根據《金融郵報》的報道,探索X射線透射(XRT)礦石分選技術——一種提高黃金回收率的技術——展示了優化項目經濟性的積極方法。 同時,與BC Hydro的合作整合可再生柴油和電氣化舉措,突顯了減少項目碳足跡的承諾,這已成為以ESG為重點的投資者日益關注的優先事項。 這些努力與全球礦業去碳化的趨勢相一致,可能會在一個日益受到可持續性指標影響的監管和市場環境中,改善項目的長期可行性。
戰略對齊與未來展望
西班牙山金礦公司在治理和運營准備方面的雙重關注為其2027年的建設決策奠定了協同基礎。 審計師更換和領導層過渡解決了內部能力限制,而技術進步和可持續發展舉措則應對了外部挑戰,如許可延誤和資本成本通脹。 對於處於開發階段的礦業公司來說,這些因素往往是項目成功與停滯之間的關鍵區別。
然而,風險仍然存在。 2025年的鑽探計劃結果將對驗証礦產資源估算(MRE)的假設至關重要,而可行性研究的延遲可能會將建設決策推遲到2027年以后。 此外,Leroux將原住民合作伙伴關系整合到項目治理框架中的能力將決定監管審批的速度。 投資者必須密切關注這些裡程碑,但公司的當前軌跡表明其成為生產商的道路結構良好。
結論
西班牙山金礦在2026年的戰略轉變——從審計和領導層變動到運營創新——展示了開發階段的礦業公司如何減輕風險並提升價值。 通過優先考慮治理嚴格性和技術准備,公司正在為利用黃金行業的長期基本面做好准備,同時應對現代資本市場的ESG要求。 對於投資者來說,問題不再是項目能否推進,而是它能多快執行其雄心勃勃的時間表
新聞參考
https://spanishmountaingold.com/news/2025/spa...scal-2025/
====================================
截至2025年7月3日的礦產資源量估算 (MRE)
====================================
https://investorshangout.com/images/MYImages/...timate.png
高品位K區礦床的資源量未包含在7月3日的初步經濟評估 (PEA) 中。
=============================
K區非官方估算的黄金资源量估算
=============================
截至2月26日
https://investorshangout.com/images/MYImages/...K-zone.jpg
鑽井區域:
https://investorshangout.com/images/MYImages/...argets.png
根據 K 區更新的化驗結果,以及主礦區白銀資源量與黃金資源量之比為 1.5,若K區的噸位至少達到2億噸,與主區相同,K 區在 2025 年 7 月 3 日的初步經濟評估中將新增 5 million 盎司黃金和 7 million 盎司白銀的探明 + 指示資源量。
2026 年新的初步經濟評估報告 (PEA) 的新礦產資源估算報告 (MRE) 將顯示已探明和已指示的黃金和白銀資源量(已證實儲量)分別為 9 million 盎司黃金和 13 million 盎司白銀。如果此事成真,股價將會出現爆炸性成長。
2025年的鑽探工作持續發現長段高品位金礦表明我們鑽探的區域可能靠近金礦脈網絡,而砂金的來源正是這些金礦脈。這些金礦脈在兩億年的風化作用下崩解,可見的金被腐蝕成細小的砂金。將高品位金礦納入未來的初步經濟評估將顯著改善項目的經濟效益。
“高品位”一詞的含義取決於礦床類型。西班牙山項目主要是一個大型露天礦項目,其礦石品位通常低於窄脈地下礦。在此背景下,品位接近或超過1克/噸且礦體寬度較大的礦石被視為“高品位”,對項目開發具有重要的經濟意義,尤其是在礦山運營初期。公司目前也在研究礦石分選技術,以期提高礦石品位,從而提升項目經濟效益。
====================================
圖表 - 黃金、白銀、XAU、SPA.V、SPAUF
====================================
黃金價格 周線圖 (價格僅在每日收盤時更新)
https://stockcharts.com/h-sc/ui?s=$GOLD&p...e_vignette
50 年黃金價格
https://mrci.com/pdf/gc.pdf
白銀價格 周線圖 (價格僅在每日收盤時更新日)
https://stockcharts.com/h-sc/ui?s=$SILVER&...e_vignette
50年白銀價格 (價格單位:美分)
https://mrci.com/pdf/si.pdf
礦業指數 (XAU) 周線圖
https://stockcharts.com/h-sc/ui?s=%24XAU&...9099899440
SPA.V 周線圖
https://stockcharts.com/h-sc/ui?s=SPA.V&p...e_vignette
SPA.V - 新聞、交易數據
https://www.stockwatch.com/Quote/Detail.aspx?C:SPA.V
SPAUF.OTCQB 周線圖
https://stockcharts.com/sc3/ui/?s=SPAUF&p...e_vignette
SPAUF.OTCQB 二級
https://www.otcmarkets.com/stock/SPAUF/overview
S3Y.FSE
https://ca.finance.yahoo.com/quote/S3Y.F/char...NlcyI6e319
=========
技術分析
=========
https://investorshangout.com/images/MYImages/...SPA.VM.jpg
https://investorshangout.com/images/MYImages/...alysis.png
https://investorshangout.com/images/MYImages/...alysis.png
SPA.V weekly
https://stockcharts.com/sc3/ui/?s=SPA.V&p...8609492691
看漲頭肩形態案例
https://investorshangout.com/images/MYImages/...istory.png
=========
勘探潛力
=========
西班牙山黃金 近期鑽探工作持續發現長段金礦化,其中包括顯著的高品位礦段,其品位通常高於項目整體平均品位。公司正重點勘探並確認這些高品位礦化區域,以期提升項目經濟效益。
金品位及礦段詳情
項目整體品位:2025年初步經濟評估(PEA)中,已探明和已控制礦產資源的平均品位約為0.44克/噸。
高品位礦段:近期勘探鑽探計劃旨在確定可納入未來礦山規劃的高品位礦化帶。這些勘探項目已取得多個顯著的高品位礦段:
其中一個鑽孔截獲了123.00米、平均金品位為1.08克/噸的礦段,其中包括一段47.28米、平均金品位為2.29克/噸的高品位礦段。
另一個鑽孔截獲了一段107.50米、平均金品位為0.68克/噸的礦段,其中包括一段41.00米、平均金品位為0.98克/噸的礦段。
鑽探還証實,在一段更寬的96.47米、平均金品位為0.91克/噸的礦段內,存在一段29.00米、平均金品位為2.55克/噸的連續高品位礦段。
在新的 Orca 斷層區域進行的近地表鑽探也顯示出多處長截礦段,例如35.80米、金品位1.18克/噸和41.00米、金品位0.98克/噸。
“高品位”的定義
“高品位”一詞與礦床類型相關。西班牙山項目主要是一個大型露天礦項目,其平均品位通常低於窄脈地下礦。在此背景下,品位接近或超過1克/噸且礦體寬度較大的礦段被認為是“高品位”,對項目的開發具有重要的經濟意義,尤其是在礦山運營初期。公司還在研究礦石分選技術,以期提高礦石品位並改善項目經濟效益。
=======================
認股權証、期權、內部股權
=======================
https://investorshangout.com/images/MYImages/...302026.jpg
內幕交易更新
https://www.barchart.com/stocks/quotes/SPA.VN/insider-trades
https://www.canadianinsider.com/company-insid...cker=SPA.V
========================
生產基礎設施建設融資計劃
========================
黃金價格
方案 1 - 與一家資金雄厚的礦業公司合資
方案 2A - 債務融資 (採用XRT選礦技術)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 2B - (無XRT選礦技術,處理所有岩石)
https://investorshangout.com/images/MYImages/...ology).jpg
方案 3 - 收購交易
British Columbia Golden Triangle 地區的歷史收購交易
Placer Dome 和 International Corona 以每股 $67 收購 Stikine Resources
https://www.northernminer.com/news/placer-sta...000178407/
Imperial Metals 以每股 $2.45 收購 American Bullion Minerals Ltd.
https://imperialmetals.com/for-our-shareholde...an-bullion
Newmont 以每股 $3.25 收購 GT Gold,交易金額達 $393 million
https://www.newmont.com/investors/news-releas...fault.aspx
澳大利亞黃金和銅生產商 Newcrest Mining 以 每股 $18.5 收購 Pretium Resources, 交易金額達 $3.84 billion
https://magazine.cim.org/en/news/2021/newcres...e%20region
在 Ontario, Kinross 以 每股 $32 收購 Great Bear Resources, 交易金額達 $1.8 billion
https://www.globalminingreview.com/finance-bu...resources/
=============================
初步經濟評估及 NI-43-101 技術報告
=============================
https://investorshangout.com/images/MYImages/...67_PEA.png
初步经济评估 (Preliminary Economic Assessment Economics)
https://spanishmountaingold.com/project/preli...economics/
August 18, 2025 - NI-43-101 技術報告 (Technical Report)
https://spanishmountaingold.com/site/assets/f...-final.pdf
===========================
25家金礦生產商的總體維持成本
===========================
https://www.mining.com/wp-content/uploads/202...31425A.gif
什麼是總維持成本 (AISC)?
採礦業(尤其是黃金行業)的總維持成本 (AISC) 包括所有運營成本、維持性資本支出以及維持當前生產相關的其他成本。這包括現金成本、維持性資本支出、一般及行政管理 (G&A) 費用以及環境成本和礦場關閉成本。
總維持成本明細:
現金成本:
這些是採礦和加工的直接成本,包括勞動力、能源、消耗品和特許權使用費(扣除副產品抵扣)。
持續性資本支出:
這些是維持當前生產水平所需的投資,例如設備更換、礦山開發以及維持礦山當前產能所需的其他成本。
一般及行政管理 (G&A) 費用:
這些是與運營公司辦公室和其他支持礦山運營的行政職能相關的成本。
環境及關閉成本:
這些包括與環境修復和礦山關閉相關的成本,例如復墾和退役。
勘探費用(維持性):
這些是維持當前生產水平和替換枯竭資源所需的勘探成本。
總維持成本 (AISC) 是一項綜合指標,旨在更全面地反映開採一盎司黃金的總成本,而不僅僅是直接現金成本。
======================
促成建造決策的關鍵步驟
======================
西班牙山黃金 表示,生產基礎建設會在 2026年做出決定,之后將開始進入為期兩年的建設階段。這一時間安排確保了正在進行的鑽探計劃、新的礦產資源估算(MRE)和新的初步經濟評估(PEA)在2026年下半年完成,以及所有推進項目開發所需的報告和審批手續的順利取得。新的PEA和MRE是優化項目建設的關鍵步驟。在做出建設決定之前,完成所有技術報告和監管審批是必要環節。
======
概述
======
礦業項目可以通過替代融資(例如流融資、礦權使用費融資或合資企業)在實現收入之前償還貸款。這些融資方式的限制比傳統債務更少,並且可以使用未來產量或收入作為抵押品,而不是現有收入。其他方法包括獲得政府補助和獎勵、通過包銷協議預售部分未來產量,以及通過發行股票籌集股本。
===============
收入前融資方法
===============
流式協議:據 Stikeman Elliott 稱,一家公司提供前期資本,以換取礦山未來礦產產量的一定比例,通常以折扣價出售。
特許權使用費融資:據 Stikeman Elliott 和 Lexology 稱,融資方為項目提供資金,以換取項目未來收入或利潤的一部分,這可以被視為對項目潛力的認可。
合資企業:與其他礦業公司或投資者合作可以分攤成本,分散財務負擔,www.altfin.net 指出。
包銷協議:將未來礦產產量的一部分預售給買家可以獲得前期融資,並使貸款方對項目潛力充滿信心。
政府資助:據 www.altfin.net 稱,政府和開發銀行有時會為符合經濟或環境目標的項目提供贈款、貸款或稅收優惠。
股權融資:通過發行股票籌集資金通常被認為是早期項目最簡單的途徑,因為它避免了債務融資的復雜性和嚴格要求。
這些方法的優勢:
非稀釋性(針對礦流/特許權使用費):Stikeman Elliott 指出,這些選擇不會稀釋公司原有股東權益。
靈活的條款:Appian Capital Advisory LLP 表示,礦流和特許權使用費結構比傳統銀行債務更靈活、限制更少,允許定制還款方案。
市場信心:礦流和特許權使用費等協議可被視為市場對項目的認可,從而可能增強投資者信心。
=========
盈利前景
=========
西班牙山黃金 近期更新的初步經濟評估 (PEA) 顯示其經濟前景良好,基准情景下淨現值 (NPV) 為 $1 billion,內部收益率 (IRR) 為 18.2%,隨著金價上漲,淨現值 (NPV) 和內部收益率 (IRR) 可能分別升至 23 億加元和 32.0%。盡管該公司仍處於早期開發階段,但該項目的傳統露天開採、銑削作業、基礎設施使用權以及具有施工和運營經驗的新管理團隊為其潛在的成功做出了貢獻。
支持盈利能力的因素:
良好的經濟效益:初步經濟評估 (PEA) 預計,該項目將帶來可觀的財務回報,稅后淨現值 (NPV) 為 $1 billion, 內部收益率 (IRR) 為 18.2%,基准金價為 2,450 美元/盎司﹔現貨金價為 3,300 美元/盎司時,回報將更加可觀。
強大的資源信心:經濟分析基於高度的資源信心,涵蓋了已探明和已指示的資源量,這些資源量是採礦項目成功的關鍵。
經驗豐富的管理層:自 2022 年起,公司組建了新的董事會和管理團隊,在項目管理、建設和運營方面擁有數十年的經驗,為公司制定生產決策奠定了基礎。
發達的基礎設施:該項目將受益於不列顛哥倫比亞省中部完善的基礎設施,包括公路交通便利以及毗鄰威廉姆斯湖市的優勢,從而降低運營復雜性和成本。
戰略項目設計:該公司計劃採用傳統的露天開採和銑削作業,這是一種低風險的方法,比地下採礦更簡單。