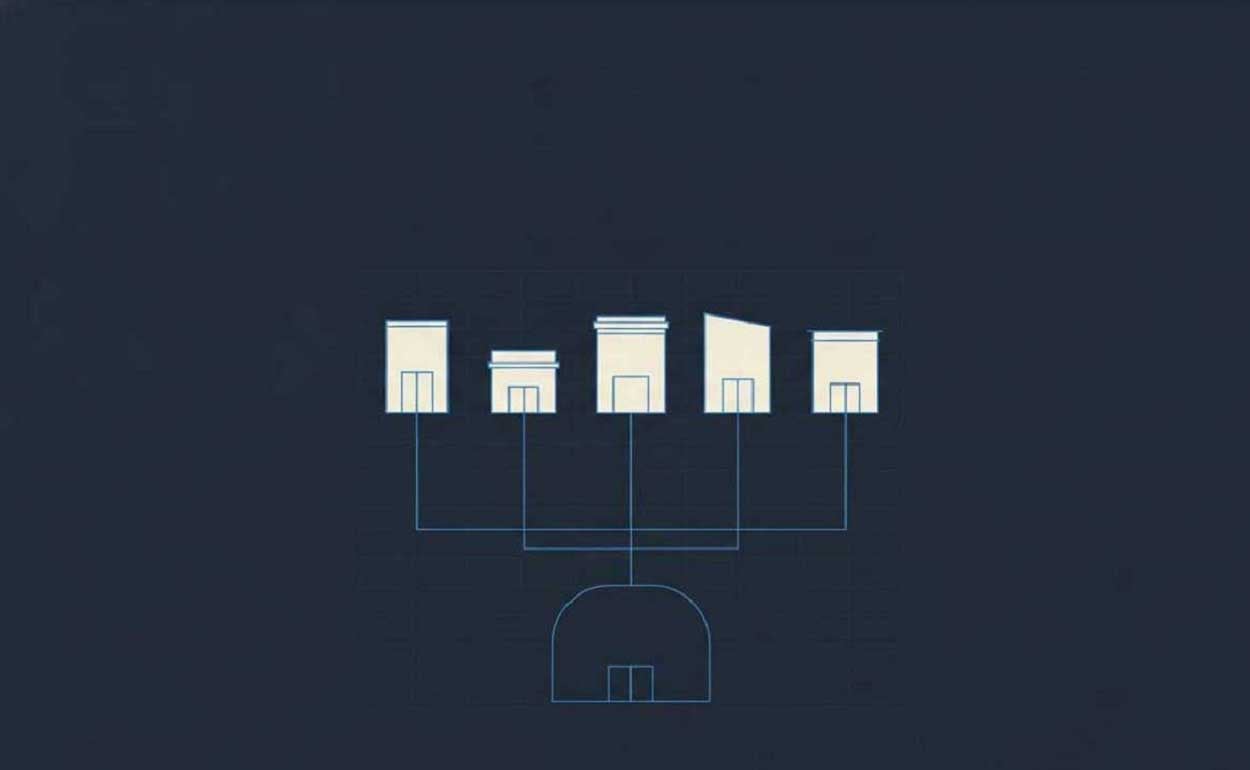
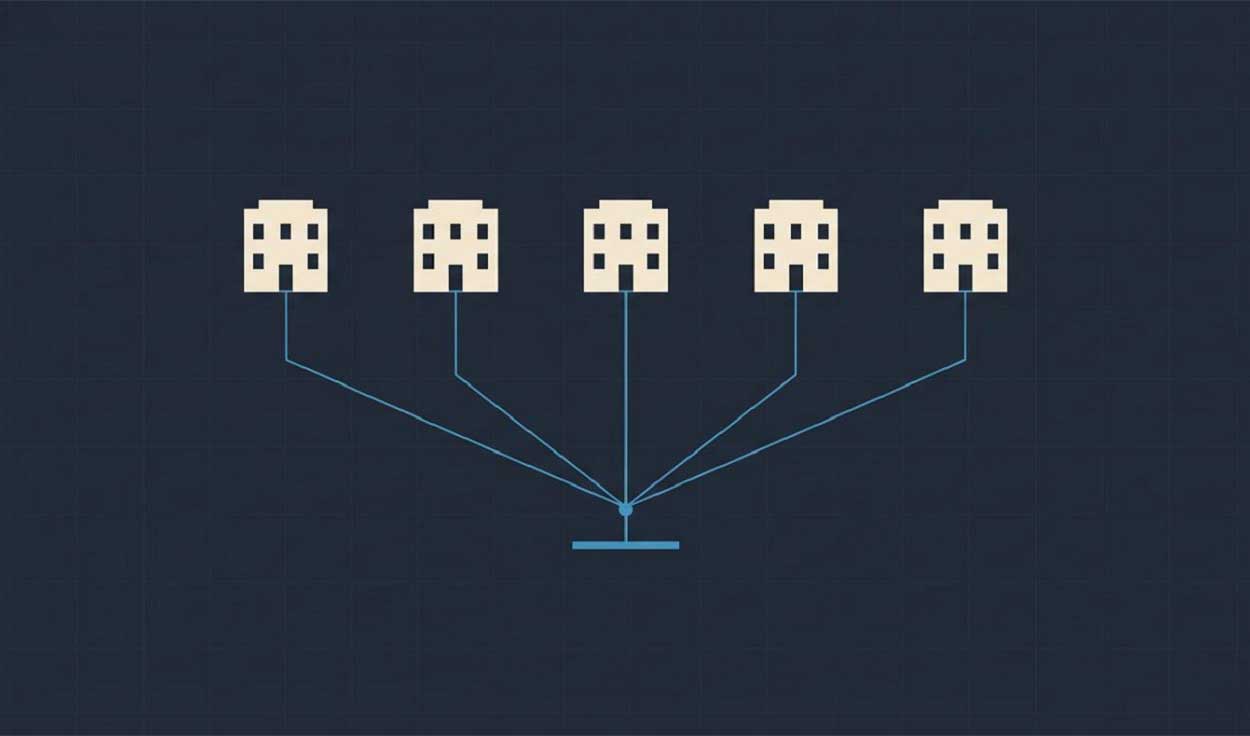
A brand name on a trading platform says less about who operates it than most users assume. A large share of retail-facing platforms are white-label deployments: one piece of software, one back office, one liquidity arrangement, resold under many names by companies that did not build any of it.
This is a legitimate and ordinary arrangement. It is also the single most useful thing to establish before depositing, because it determines who answers when something goes wrong. An overview of what a white label trading platform is covers the structure; what follows is how to read it from the outside.
One consequence up front: review records become much more useful once you know which company you are reading about. Platforms such as WebVouch confirm the transaction before an entry appears and read an operator by how long and how evenly its record accumulated, and the business has no way to delete what it dislikes.
What the Arrangement Actually Is
A technology provider builds the platform and licenses it. A separate company handles branding, marketing and customer acquisition, and holds the client relationship. Depending on the deal, a third entity may hold the licence under which the investing activity is conducted.
The user sees one brand. Behind it sit two or three companies with different obligations, and the split determines everything about what happens in a dispute.
The reason to care is not that white labelling is improper. It is that support quality, complaint handling and regulatory standing attach to the branded operator, while the platform behaviour everyone reviews attaches to the technology provider. Reviews praising the software and reviews complaining about withdrawals are frequently describing two different companies.
How to Spot It in Ten Minutes
Several markers show up reliably.
Read the terms of service and note every legal entity named. If the company you signed up with is not the one processing funds, that is the structure.
Compare the interface against others you have used. White-label platforms share layouts, order-ticket designs and terminology down to the wording of error messages. Searching a distinctive phrase from the interface frequently surfaces the sibling brands.
Check where the licence, if cited, actually sits. A registration held by a parent or by the technology provider is not a registration held by the entity you are contracting with.
Look at the support address domain and the payment descriptor on the first transaction. Both routinely reveal a company the marketing never mentions.
Why It Matters When Something Goes Wrong
Three practical consequences.
Complaints route to the branded operator, not the platform. The software provider has no relationship with you and no obligation to respond. If the branded operator is small, the complaints function may be one inbox.
A failure repeats across brands. When a withdrawal process breaks at the provider level, it breaks for every brand running that deployment. A problem that looks like one company having a bad month is sometimes ten companies sharing an outage, which is visible only if you know they are connected.
Regulatory recourse depends on the contracting entity. The protections available are those of the jurisdiction where that entity is licensed, regardless of where the platform was built or where the marketing is aimed.
Reading the Review Record With This in Mind
Once the structure is understood, review evidence becomes considerably more informative for anyone evaluating an investing platform.
Separate the reviews about software behaviour from the reviews about the company. The first tell you about a product used by many brands. The second tell you about the operator you are actually dealing with, and those are the ones that predict your experience.
Weight the distribution over the average. Steady arrival across many months is hard to manufacture; a cluster of praise in one week is a campaign, and the shape is the part that cannot be bought cheaply.
Pay particular attention to reviews describing withdrawals and support response times. Those are the operator-specific functions, and they are where white-label investing platforms differ most from one another despite running identical software.
A Short Pre-Deposit Routine
Name the entity in the terms. Confirm the licence sits with that entity. Complete verification fully and withdraw a small amount before committing anything material. Read the operator-specific reviews rather than the platform ones.
The withdrawal test is the one that cannot be substituted. Everything else is documentary, and documents describe intentions. A completed withdrawal describes the thing itself.
Do it before the account holds anything you would mind waiting for. The point of the exercise is to learn how the process behaves while the answer is cheap, and the fees involved are the smallest amount anyone will ever pay for that information.
The General Point
Brand names are the cheapest layer of any financial service to produce, and the layer most users treat as identifying. Knowing which company is behind the name costs a few minutes and changes what the rest of the evidence means.
It is also worth repeating periodically. Operators change providers, licences move, and the entity named in the terms today may not be the one named next year. Terms updates arrive by email and go unread, which is where these changes usually hide.